Uncategorized

Selecting Event Liability Limits requires brokers to do far more than match a policy to a contract requirement. Special event insurance is designed to help protect hosts from financial losses arising from covered accidents, bodily injury, or property damage during an event. Selecting appropriate limits requires brokers to evaluate how a special event’s unique exposures translate into the right level of protection. While venue contract insurance requirements often establish minimum event liability limits, brokers must also consider factors such as expected crowd size, public accessibility, alcohol service, and higher-risk activities that can significantly increase the likelihood and severity of claims. The appropriate liability limit depends on the event’s contractual obligations, attendance, planned activities, venue characteristics, and the potential severity of a claim rather than a one-size-fits-all recommendation.

The goal of Selecting Event Liability Limits is not simply to satisfy contractual obligations, but to ensure insurance coverage aligns with the real-world risks of a special event. By balancing venue contract insurance requirements with exposure-driven risk analysis, brokers help clients secure event liability limits that are both compliant and defensible when a loss occurs, while meeting the underwriting expectations of the insurance company providing coverage.

The Insurance Policy Contract Limit Sets the Floor, Not the Ceiling

When selecting event liability limits, it’s important to remember that the insurance requirement outlined in a venue contract or municipal permit is only the starting point. These minimum municipal permit insurance limits are designed to satisfy contractual obligations, but they may not fully reflect the event’s actual exposure to risk. The per-occurrence limit represents the maximum amount available for a single covered claim, while the general aggregate limit represents the maximum available for all covered claims during the applicable policy period. Both limits should be reviewed carefully because satisfying a venue’s per-occurrence requirement does not necessarily mean the aggregate limit provides adequate protection for the event as a whole.

Public events often face greater liability exposure because organizers have less control over attendees and their actions, increasing the potential for accidents, injuries, property damage claims, and costly legal fees. In these situations, securing adequate public event liability coverage may require limits that exceed contractual minimums. Brokers should look beyond the certificate of insurance (COI) limits specified by the venue and carefully evaluate key event details, including attendance, public access, event duration, venue characteristics, and planned activities. By treating contractual requirements as the floor rather than the ceiling, brokers can help clients obtain insurance coverage and event liability limits that better align with real-world exposures and provide stronger financial protection when unexpected incidents occur.

Crowd Size and Footprint: The Fastest Limit Escalator

When determining event liability limits, few factors influence exposure more quickly than crowd size and event footprint. While attendance numbers are among the most significant event insurance cost drivers, they also play a major role in the potential severity of a claim and a venue’s crowd size risk rating assessment. As crowds grow, the likelihood of incidents involving slips and falls, crowd surges, bottlenecks, or emergency evacuation challenges increases, particularly in venues with tight spaces, long entry lines, or limited exits. These risks can be amplified by unforeseen circumstances, such as severe weather, power outages, or unexpected surges in attendance.
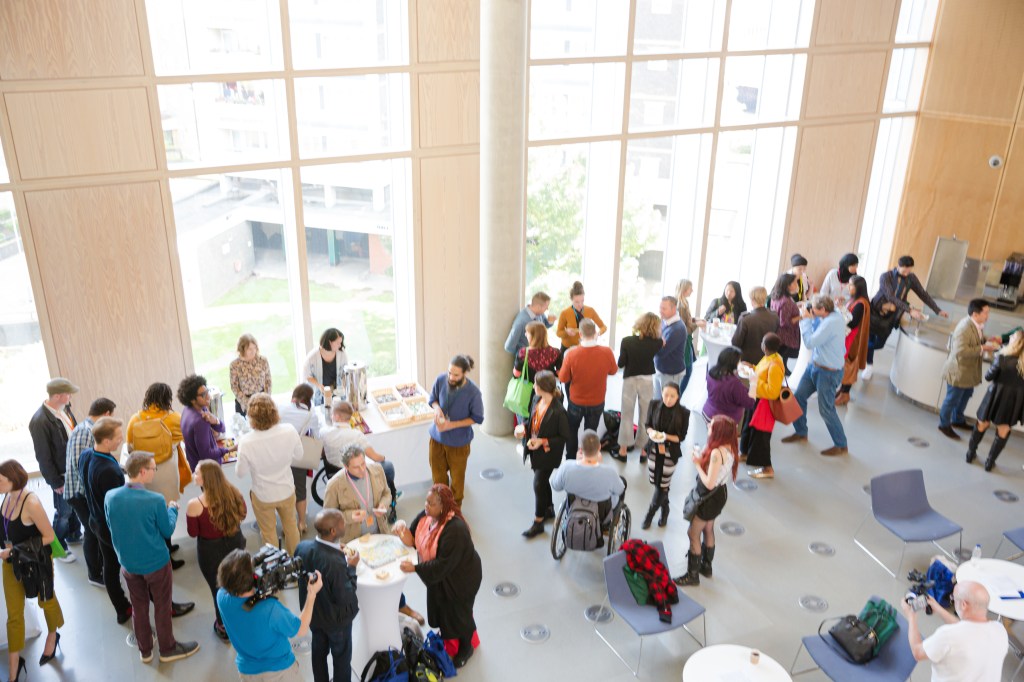
Busy conference reception illustrating how event size and attendance can influence the selection of event liability limits.

Larger event footprints further increase exposure by expanding the areas organizers are responsible for managing and monitoring. For this reason, underwriters, venues, municipalities, and the insurance provider evaluating the risk often require higher event liability limits as attendance and venue size increase. Whether covering festivals, private parties, school-sponsored events, hiking events, private fundraising auctions, or large corporate gatherings, organizers may also face stricter contractual language, additional insured requirements, and more rigorous risk management expectations.

By evaluating both the number of attendees and the physical layout of the event, brokers can recommend event liability limits that reflect the heightened exposure associated with larger, more complex gatherings while addressing key event insurance cost drivers, preparing for unforeseen circumstances, and supporting a more accurate crowd size risk rating.

Liquor Liability and Other Activities That Change the Limit Conversation

Not all event risks are driven by attendance. Certain high-risk event activities can significantly increase claim severity and influence event liability limits, even when crowd sizes remain relatively small. Any event involving alcohol service, inflatables, live entertainment stages, sporting activities, rides, or vehicle-related operations introduces unique exposures that can lead to serious injuries, property damage, and increased legal liability. For example, alcohol service can create substantial risk because an intoxicated guest may cause bodily injury or property damage during or after the event. Host liquor liability may protect an event host when alcohol is served free of charge and no money is exchanged for it.

Standard general liability insurance may exclude or restrict alcohol-related incidents, making it important to confirm whether host liquor liability coverage is included or must be added. The broker should review how alcohol will be supplied, served, and paid for before determining which form of liquor liability coverage is appropriate. This distinction is especially important when arranging wedding insurance or coverage for other private parties. Clients should not assume that homeowners insurance will provide comprehensive protection for an event held away from home, particularly when alcohol, rented premises, vendors, or contractual venue requirements are involved.

Likewise, stages, athletic competitions, and vendor vehicle access can elevate risk beyond what attendance figures alone would suggest. When these higher-hazard activities are present, brokers often recommend increased primary liability limits along with umbrella insurance for events to provide additional layers of protection and help satisfy venue or municipal contract requirements. By evaluating both attendance and the specific activities planned, brokers can structure coverage that better aligns with the event’s true exposure while protecting clients against the potentially severe claims, legal liability, and financial consequences associated with any event involving high-risk operations, host liquor exposure, and other activities commonly found at private events.
Event organizers discussing coverage needs and liability considerations while planning an upcoming event.

Certificate of Insurance and Additional Insured Requirements

Selecting the appropriate liability limit is only part of the event insurance equation. For events held at venues, parks, convention centers, and other public locations, organizers must also satisfy endorsement requirements that accompany those limits before coverage will be approved. Common additional insured requirements, primary and noncontributory wording, and a waiver of subrogation are frequently listed on a venue’s Certificate of Insurance (COI) checklist and are just as important as the liability limits themselves. Venues often require at least $1 million in liability coverage and must be listed as an additional insured before setup, rehearsals, or the event itself can proceed. Even when organizers secure coverage with the required policy limits, missing or incorrectly worded endorsements can result in a rejected COI and delays in obtaining venue approval.

For brokers, this means reviewing contract language as carefully as the policy itself. Although special event insurance can often be purchased online within minutes, clients should ideally secure coverage at least 30 days before the event. Venue requirements should be shared with the insurance agent upfront so that the necessary limits, additional insured endorsements, and policy wording can be included from the start.

Ensuring that endorsement requirements align with venue specifications helps clients satisfy contractual obligations, avoid administrative setbacks, and confirm that covered claims will be handled in accordance with the event’s risk transfer requirements. By properly structuring coverage for events held at third-party venues, brokers can help clients secure coverage that meets contractual expectations while protecting all parties involved when covered claims arise.

Bodily Injury, Damage to Premises, and Venue Expectations

While major liability claims often receive the most attention, many venues are equally focused on the damage-to-premises coverage included within a general liability for events policy. This is where smaller but more frequent claims tend to occur, such as scratched floors, damaged walls, broken fixtures, or minor property damage during event setup and teardown. Whether the event is a wedding, fundraiser, trade show, or corporate gathering, these incidents can create disputes between organizers and venue owners if the damage to premises rented to you limit falls short of contractual expectations.

In fact, many venues require proof that adequate property damage coverage is in place before approving an event. Brokers should carefully review venue contract insurance requirements and available coverage options to ensure the damage-to-premises sublimit aligns with the rental agreement’s property protection provisions. While often associated with physical damage, a comprehensive liability policy may also include protections for exposures such as advertising injury and medical payments. Medical payments coverage may help address certain immediate medical bills arising from an eligible guest injury, while larger bodily injury claims may fall under the policy’s liability coverage.
Insurance professional reviewing policy documents to help determine appropriate event liability coverage limits.

Adequate damage-to-premises coverage helps address common venue-related losses, supports smoother claims handling, and can prevent disagreements that may delay security deposit returns. By aligning coverage with venue expectations and exploring appropriate coverage options, brokers help clients strengthen their event insurance program, satisfy requirements where venues require proof of coverage, and protect both their finances and venue relationships during any corporate gathering or special event.

Event Insurance: Vendors and Shared Responsibility

Vendor participation can significantly influence event risk, making vendor management an important factor when determining appropriate event liability limits. On paper, vendor-heavy events may present lower exposure when each vendor carries its own liability insurance, meets established vendor insurance requirements, and provides a valid COI. Because vendors may be insured through non-affiliated insurance companies, organizers should review each certificate individually rather than assuming every policy provides identical coverage.

Reviewing COI limits helps the event host verify that vendors maintain adequate coverage for their operations and can respond to claims arising from their activities. This creates a clearer division of responsibility and supports effective risk transfer. However, when vendors are uninsured, underinsured, or fail to meet vendor insurance requirements, the organizer’s policy can become the financial backstop for incidents that would otherwise fall outside their direct responsibility, potentially increasing exposure to claims, defense costs, and settlement expenses.

This risk can be magnified when an event qualifies as a large-scale gathering or spans multiple consecutive event days, creating additional opportunities for incidents to occur. For brokers, verifying vendor compliance and confirming sufficient COI limits is a critical risk management step that helps protect the event host from unnecessary liability while ensuring that event liability limits accurately reflect the event’s true exposure rather than gaps in vendor coverage. By addressing vendor-related risks before an event qualifies for coverage and throughout consecutive event days, organizers can better control potential losses, reduce defense costs, and strengthen their overall insurance program.

Event Cancellation Insurance Protects Different Financial Risks

Liability limits address eligible claims involving injuries, property damage, and related legal expenses, while event cancellation insurance protects a different exposure. Event cancellation coverage may reimburse lost deposits and other non-refundable amounts when an event is cancelled or postponed because of a covered unforeseen circumstance.

Because event cancellation coverage serves a different purpose than liability insurance, brokers should evaluate these coverages separately. Liability insurance is designed to address covered third-party claims arising from the event, while event cancellation insurance focuses on certain financial losses associated with a covered cancellation or postponement. Reviewing both coverages independently helps ensure clients have protection that aligns with the full range of risks associated with their event.

When Umbrella Insurance Makes the Most Sense as Optional Coverage
Calendar and pen representing the planning process for selecting event liability limits before an upcoming event.

Selecting the right event liability limits often involves balancing actual event exposure with strict contractual requirements. When a venue, municipality, or event host requires liability limits that exceed standard policy offerings, umbrella insurance for events can be an efficient and cost-effective solution. Rather than restructuring the entire liability program, an umbrella policy provides an additional layer of protection above the primary coverage limits, helping organizers increase their per occurrence limit and overall aggregate limit for events while enhancing protection against claims involving bodily injury and property damage. This added layer of coverage can also help address certain forms of personal injury liability that may arise during covered events.

The approach is especially valuable when an event’s risk profile is moderate, but venue agreements impose demanding insurance requirements. Whether supporting festivals, fundraisers, conferences, or even certain political events, umbrella coverage can help bridge the gap between standard policy limits and contractual expectations. By combining appropriate primary coverage with umbrella insurance for events, brokers can satisfy venue contract obligations, extend available per-occurrence and aggregate limits, and provide more comprehensive protection against claims involving bodily injury, property damage, personal injury, and other covered liabilities. This may be particularly useful for an existing policyholder whose primary insurance policy cannot meet a new venue’s required limits on its own.

Sources:

https://www.markel.com/insights-and-resources/insights/event-insurance-guide-for-planners
https://www.abcweddingplanners.com/notebook/blog/the-importance-of-event-liability-insurance
https://www.hubinternational.com/en-CA/programs-associations/venue-users-insurance/
https://eventsguardian.com/event-liability-insurance-costs-2025/
https://www.higginbotham.com/blog/event-liability-insurance/
https://arminsco.com/event-liability-insurance-the-us
Exhibitor and vendor insurance requirements are more than just administrative paperwork, they are a critical risk-management tool that helps protect exhibitors, organizers, venues, and attendees. These exhibitor insurance requirements, vendor insurance requirements, and event venue insurance requirements create a risk-transfer system that helps ensure organizers and venues are not financially responsible for losses, damages, or incidents caused by third-party exhibitors or vendors.

Most events require exhibitors to carry general liability insurance, which can provide liability coverage for claims involving bodily injury, property damage, and, in some cases, legal fees associated with defending against covered claims. Depending on the exhibitor’s activities, vendor insurance coverage may also include product liability insurance, property insurance, workers’ compensation, liquor liability, or commercial auto insurance.

By requiring a Certificate of Insurance (COI) from a reputable insurance carrier before the event, organizers can verify that adequate coverage is in place and reduce exposure to unexpected liability. When COIs are collected early and reviewed thoroughly, the process helps prevent last-minute compliance issues, minimizes disputes during event setup and teardown, and reduces the likelihood of costly finger-pointing if a claim arises after the show. Ultimately, these insurance requirements create a safer, more accountable event environment while streamlining risk management and compliance for all stakeholders.

General Liability Insurance: The Foundation of Exhibitor Coverage

Commercial general liability coverage is usually the most important insurance requirement for an exhibitor, vendor, or trade show participant. It may respond when the exhibitor’s operations result in bodily injury or property damage, for example, if an attendee trips over booth equipment or a display damages part of the venue.

Many venues require at least $1 million in general liability coverage per occurrence, although some contracts require limits of $2 million or more. The vendor contract may also specify a minimum per-occurrence limit and aggregate limit. Exhibitors should check with every venue where they plan to set up rather than assuming one standard policy will satisfy every organizer.

Vendor liability insurance requirements may extend beyond basic premises and operations coverage. Product-based businesses, alcohol vendors, companies using vehicles, and exhibitors with employees may need additional insurance based on the exposures they bring to the event.

Certificate Holders vs. Additional Insured Endorsements Explained

One of the most common points of confusion in exhibitor insurance requirements is the distinction between a certificate holder and an additional insured. Understanding additional insured vs. certificate holder is essential for exhibitors, vendors, event organizers, and venues to ensure they have the proper coverage required by event contracts. A certificate holder is simply the party that receives a Certificate of Insurance (COI) as proof that coverage exists. While the certificate confirms that the exhibitor or vendor maintains an active insurance policy, such as a Business Owners Policy (BOP) or general liability policy, it does not provide the certificate holder with protection under that policy. Most certificate holder requirements are limited to documenting coverage and demonstrating compliance.

An additional insured, however, receives certain coverage benefits under the exhibitor’s insurance policy for claims arising from the exhibitor’s operations, activities, or presence at the event. This protection is typically granted through an additional insured endorsement, which extends specified coverage to the organizer, venue, or even a business partner when required by contract.

Additional insured status is often tied to contractual liability provisions and helps ensure that the parties named in event agreements receive the intended protection if a covered claim occurs. Although the additional insured may appear on the COI, the certificate alone does not modify the policy or guarantee that coverage has been extended; the insurer must issue the appropriate endorsement. The cost of adding an additional insured is generally low because many insurers consider the additional exposure marginal, although pricing and availability can vary.

For this reason, many vendor insurance requirements and event venue insurance requirements specifically require organizers and venues to be named as additional insureds rather than merely listed as certificate holders. Understanding the difference helps ensure compliance with contractual obligations, secures proper coverage, and reduces disputes when claims arise.

Exhibitor COI Requirements: Why Named Insured Verification Matters

A well-prepared exhibitor COI is a critical component of meeting insurance requirements and ensuring smooth event compliance. A good COI should clearly identify the named insured, policy types, coverage limits, policy effective dates, and insurer information, leaving no ambiguity about who is covered under the policy. Completing proper named insured verification is especially important, as the business name listed on the certificate should exactly match the exhibitor’s legal entity name. This helps ensure the correct party is insured and prevents coverage disputes that could leave an exhibitor paying for losses out of their own pocket.

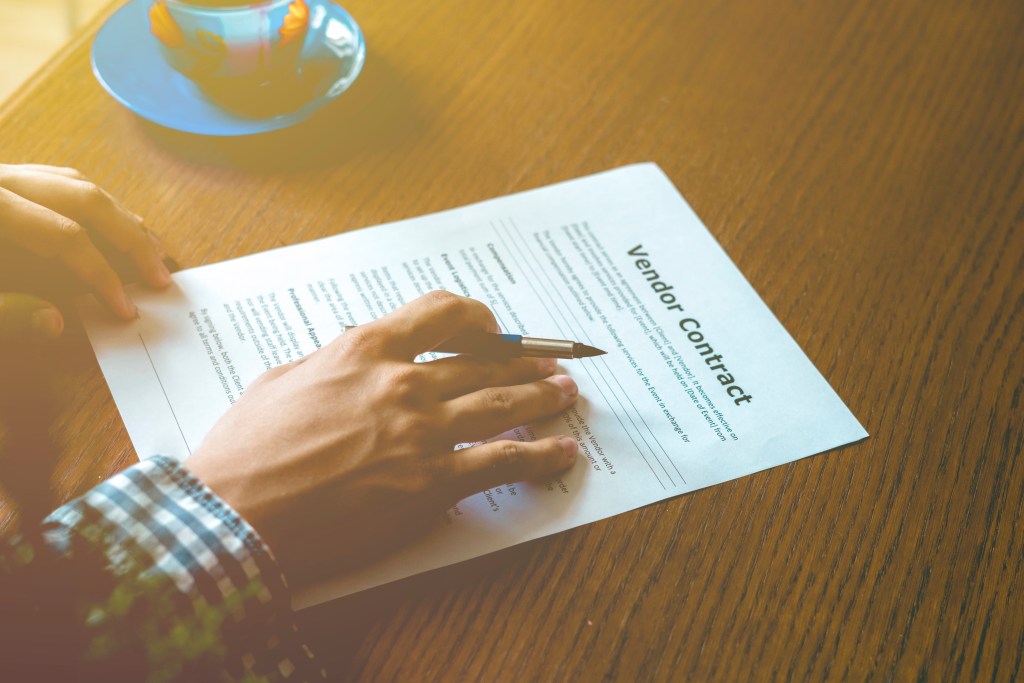
Close-up of a vendor contract being signed, representing the documentation that often outlines exhibitor insurance requirements, additional insured endorsements, and required insurance coverage for participating vendors.

The COI should also include accurate details for the specific event, such as the venue name, event title, and event dates, along with any required endorsements, including an additional insured endorsement when requested by the organizer or venue. Using a thorough COI review checklist helps organizers and exhibitors confirm that all required information is present and compliant before the event. Proper coverage is essential because claims involving injuries could result in medical costs, lost wages, and other expenses that may not be covered if certificate information is inaccurate or incomplete.

By ensuring every detail aligns with vendor insurance requirements and event venue insurance requirements, exhibitors can avoid delays, reduce compliance issues, and demonstrate that they have the appropriate protection in place before arriving on-site.

Insurance Policy Effective Dates: The Most Common Compliance Failure

One of the most frequent reasons an exhibitor COI is rejected is incorrect or insufficient coverage dates. The effective date is typically the date on which the vendor needs insurance to begin, often coinciding with the first day of access rather than the first public show day. Many organizers require vendors and exhibitors to carry insurance throughout move-in, installation, show days, dismantling, and move-out activities. Failing to verify COI effective dates for events can create significant exposure because coverage gaps may leave exhibitors or organizers held responsible for incidents that occur outside the policy period. This is particularly important for special events, where property damage and bodily injury claims often arise during booth setup and teardown rather than while the event is open to attendees.

A thorough COI review checklist should confirm that coverage applies throughout the entire event timeline, from the first day exhibitors access the venue through the final day of move-out. Adequate coverage during setup and dismantling helps protect and cover exhibitors, organizers, and venues against unexpected claims and is a critical component of event venue insurance requirements. By carefully reviewing coverage periods and ensuring compliance with vendor and venue requirements, event organizers can avoid one of the most common compliance failures, reduce risk, and better protect all parties involved.

Exhibitors purchasing event-specific vendor insurance coverage should not leave the application until the last minute. Coverage can often be obtained in less than 24 hours by completing an online enrollment form or submitting an application to the insurance provider as directed, but underwriting questions, endorsements, or certificate corrections may require additional time.

Insurance Coverage Limits, Deductibles, and Contract Alignment

Organizers typically set minimum insurance coverage limits based on venue contracts, expected attendance, and the risks associated with exhibitors’ products and services. Many venues require exhibitors and vendors to carry specific levels of coverage to protect against accidents, injuries, and third-party property damage liability that may occur during an event. The vendor contract should identify the types of insurance required, minimum per-occurrence and aggregate limits, parties that must be added as additional insureds, and any other required policy wording. Vendors should review the contract before applying and check directly with every place where they will be setting up to confirm that their protection meets the venue’s requirements. This is especially important for small businesses, which may be participating in trade shows, conferences, or special events with limited risk-management resources.

Equally important are the limits and deductibles for vendors, as high deductibles can impact how quickly claims are handled and increase the out-of-pocket cost of resolving property damage disputes. By reviewing both coverage limits and deductible amounts, organizers can help ensure compliance with event requirements, reduce financial risk, and confirm that exhibitors have adequate protection in place.

Event organizer reviewing contracts with exhibitors before a show, highlighting the importance of confirming exhibitor insurance requirements, certificates of insurance, and liability coverage before the event begins.

Business Owner’s Policy vs. Event-Specific General Liability

Some established exhibitors may already carry their own insurance through an annual commercial policy. A business owner’s policy, commonly called a BOP, combines commercial general liability and commercial property insurance under one policy, often at a lower cost than purchasing the coverages separately.

However, having a BOP does not automatically mean every exhibitor insurance requirement is satisfied. The exhibitor should confirm that the planned activities are covered, the limits are high enough, and the insurer can provide any required additional insured endorsements, primary and noncontributory wording, or waiver of subrogation.

For occasional vendors or businesses without suitable annual coverage, event-specific general liability insurance may provide a more direct option. Whichever approach is used, the policy must align with the actual requirements in the vendor and venue contracts.

Exhibitor Insurance Requirements: Additional Insured Endorsements And Other Venue Requirements

Many event venue insurance requirements go beyond providing basic proof of coverage and include specific endorsements that help manage risk and handle potential claims. In fact, many venues require vendors and exhibitors to carry endorsements such as an additional insured endorsement, primary and noncontributory wording, and waiver of subrogation wording. These endorsements work alongside the exhibitor’s underlying policy to clarify how coverage applies and which party’s insurance will respond first in the event of an incident. They are particularly important for protecting venues and organizers from third-party claims involving bodily injury, property damage, or other liabilities arising from exhibitor activities.

Even if these requirements are listed on a Certificate of Insurance (COI), approval can be delayed if the actual endorsements have not been formally issued by the insurer. To avoid compliance issues and claim-related disputes, exhibitors should verify that all required endorsements are attached to their policy and properly documented before submitting their COI. Taking this extra step helps ensure a smoother approval process, demonstrates compliance with venue requirements, and reduces the risk of coverage gaps when claims occur.

Other Coverage Trade Show Exhibitors May Need

General liability is foundational, but it does not cover every exposure associated with exhibiting at a trade show, conference, market, or special event. Depending on the operation, an exhibitor may also need property insurance, product liability insurance, workers’ compensation, commercial auto, liquor liability, event cancellation, or commercial umbrella insurance.

Product liability insurance covers certain claims involving bodily injury or property damage caused by defective products. Specialized property insurance may help cover theft, fire, or accidental damage to displays, inventory, equipment, and other materials while they are at the show, stored off-site, or travelling in transit.

Workers’ compensation insurance may be required when a business has employees working at its booth. Requirements vary by state, but most states require businesses with eligible employees to carry coverage at statutory limits. It can cover medical bills and a portion of lost wages arising from work-related injuries and illnesses.

Commercial auto insurance may be necessary when business-owned or business-used vehicles are involved in event operations, including food trucks and delivery vehicles. Liquor liability insurance is often required for vendors selling or serving alcohol and may cover eligible legal fees, property damage, and medical costs resulting from alcohol-related incidents.

Event cancellation insurance may reimburse certain non-refundable expenses if a show is cancelled or interrupted by a covered unforeseen circumstance. Commercial umbrella insurance can provide additional limits above general liability, commercial auto, or employer’s liability coverage once the applicable underlying limit has been reached.

Not every exhibitor needs all these coverages. The appropriate combination depends on the exhibitor’s products, activities, employees, property, contractual obligations, and venue requirements.

Common Gaps: Exclusions and “Not Covered” Scenarios

Even when an exhibitor meets basic insurance requirements, policy exclusions and gaps can create unexpected coverage issues that may leave important risks uninsured. Certain activities, products, or higher-risk operations commonly associated with conference vendor insurance may not be covered under a standard policy, making it essential to verify that policies provide coverage for all planned event activities. This is especially important when exhibitor activations involve live demonstrations, product sampling, specialized equipment, alcohol, vehicles, or completed operations. For example, standard general liability coverage may not protect the exhibitor’s own booth materials against theft or accidental damage, and it may exclude certain product-related, professional service, cyber, or liquor-related losses.

In some cases, exclusions related to a policyholder’s business activities or policyholders’ actions can limit coverage for incidents that occur during an event. Cyber insurance may also be worth considering when an exhibitor collects customer information or processes electronic transactions. It can help address certain costs associated with data breaches, hacking, or malicious software attacks, subject to the policy’s terms and exclusions.

A careful review of policy exclusions, limitations, and endorsements can help identify potential risks before the event and prevent unexpected claim denials. While expanding coverage may increase the overall cost of insurance, it can also help protect exhibitors from uncovered losses and liability exposures. By addressing coverage gaps early, organizers and exhibitors can better safeguard themselves against claims, compliance issues, and costly disputes that arise after the event.

How Organizers Should Inspect and Track COIs

Outdoor vendor market with shoppers visiting temporary booths, representing community events and festivals where exhibitor insurance requirements often include proof of vendor insurance coverage and liability protection.

A consistent review process can make COI compliance much easier to manage and help ensure exhibitors have the protection needed if third-party lawsuits arise. Using a comprehensive COI review checklist, organizers should verify key details such as the named insured, coverage limits, required endorsements, and policy dates. Confirming that coverage is accurate and complete helps determine whether the insurance provides coverage for potential event-related liabilities and whether exhibitors may have to pay out of pocket for uncovered claims.

Tracking each exhibitor certificate of insurance (COI) and vendor certificate of insurance by exhibitor name, booth number, and submission status helps keep records organized and ensures missing or non-compliant certificates are identified early. This process is especially important for exhibitors that provide professional services, as their activities may require specialized coverage beyond standard general liability insurance. During busy conference and trade show seasons, a structured tracking system streamlines compliance efforts, reduces last-minute issues, and helps organizers confirm that coverage protects exhibitors, venues, and event organizers while remaining aligned with event venue insurance requirements and exhibitor insurance standards.

Making Requirements Broker-Friendly

Clear and well-defined exhibitor insurance requirements, vendor insurance requirements, and event venue insurance requirements help reduce friction for exhibitors and speed up the approval process for organizers. When brokers are provided with exact coverage limits, event dates, required endorsements, and venue-specific requirements, they can secure trade show exhibitor insurance that meets compliance standards on the first submission. Clear communication also helps the insurance company issue the proper documentation and endorsements without unnecessary revisions or delays. Rather than simply asking exhibitors to “provide proof of insurance,” organizers should identify the required policy types, per-occurrence and aggregate limits, additional insured names, venue details, event dates, and submission instructions.

Requirements such as an additional insured endorsement, primary and noncontributory wording, and waiver of subrogation wording are designed to address potential third-party liability exposures and ensure the appropriate parties are protected if a claim occurs. In the event a person is injured at a trade show or conference, the proper coverage may help pay for damages, including medical bills, subject to the terms and conditions of the policy. A broker-friendly approach leads to faster approvals, fewer compliance issues, and a smoother event planning experience while helping ensure exhibitors, venues, and organizers are properly protected.

Busy trade show exhibition hall with vendor booths and attendees, illustrating the type of event where exhibitors are commonly required to carry vendor liability insurance and general liability coverage before participating.

Sources:

https://smartcompliance.co/blog/certificate-holder-vs-additional-insured
https://www.exhibitoronline.com/topics/article.asp?ID=2629
https://www.trustlayer.io/resources/conference-season-checklist-exhibitor-vs-vendor-insurance–who-needs-what-and-when
https://www.insureon.com/blog/vendor-insurance-requirements-guide
https://eventhub.net/blog/2019/06/14/how-to-inspect-an-exhibitors-coi/
https://getjones.com/blog/vendor-certificate-of-insurance-guide/

Receptions and mixers bring together several of the most common event liability exposures in a single setting, including large crowds, live music, busy social environments, slippery walking surfaces, and alcohol service. Event liability insurance and special event insurance can help address these risks, but alcohol service may create additional coverage considerations. While these gatherings are designed to create enjoyable networking and social opportunities, they can also increase the likelihood of accidents, injuries, and other liability claims. Alcohol-related incidents are often a particular concern because the consequences can extend beyond the event itself, creating potential exposures both on and off the venue premises.

This is why many venues place special emphasis on alcohol risk and include specific venue liquor insurance requirements for events where alcohol will be served. In many cases, organizers may need host liquor liability insurance to help address claims arising from intoxication-related incidents when alcohol is provided to guests but not sold. This coverage can help fill important gaps in a homeowners policy or general liability policy, making it an important component of the event’s broader risk management strategy.

Host liquor liability coverage is generally intended for individuals and organizations whose regular business operations do not involve selling, serving, furnishing, or manufacturing alcohol. Businesses that serve or sell alcohol regularly typically need liquor liability insurance, which provides broader protection for alcohol-related incidents arising from their ongoing operations. By understanding and planning for these risks, organizers can host memorable events while demonstrating a commitment to guest safety, responsible alcohol service, and venue compliance.

Host Liquor Liability Insurance for Hosted and Open Bars

Venues often ask detailed questions about how alcoholic beverages will be served because the service structure can have a significant impact on event risk. Whether guests are served through a hosted bar, an open bar, a cash bar, drink tickets, or a limited tasting format, each approach creates a different exposure profile and may influence the insurance requirements for the event. For example, open bars can increase the potential for overconsumption, while drink ticket programs and tasting events may help encourage more controlled service.

Depending on the location, organizers may also need to comply with local regulations or obtain a liquor license when serving alcohol. Getting a quote for host liquor liability insurance is usually straightforward. The insurance company will generally ask for basic event details such as the date, venue address, guest count, event duration, and specifics about how alcohol will be served. These details also influence pricing, with guest count, location, and duration among the most important cost factors. Coverage for a small wedding may be available for as little as approximately $66 through some providers, although wedding host liquor coverage more commonly falls between $100 and $500. Actual pricing depends on the event and the coverage selected, so organizers should obtain a quote rather than relying on a general estimate.

Regardless of the service model, venues typically expect organizers to implement safeguards such as trained bartenders, ID verification procedures, monitored service areas, and access to food and nonalcoholic beverages. These precautions are especially important for weddings, where alcohol may be served during the rehearsal dinner, ceremony, reception, or another related gathering. Most wedding liability policies cover related events within a defined period, often a 72-hour window, but organizers should confirm the exact dates and activities included in their policy. In addition, the way alcohol is served may affect the liability limits required by venues or outlined in event contracts. By selecting a service structure that aligns with the event’s goals and risk profile, organizers can support responsible alcohol service, reduce the potential for incidents related to drunk driving, meet venue requirements, and create a safer experience for guests when serving alcohol at their event.

How Host Liquor Liability Insurance Fits with General Liability Insurance

General liability insurance provides valuable protection for many common event-related risks, including third-party bodily injury claims and property damage that may occur during a reception, mixer, or wedding ceremony. However, accidents and alcohol-related incidents can arise from unforeseen circumstances, creating exposures that may extend beyond the event itself.

Understanding the differences between general liability and liquor liability insurance can help organizers evaluate the right coverage for their event. General liability coverage addresses a broad range of claims involving bodily injury or property damage, while host liquor liability focuses on risks associated with serving and consuming alcohol. Depending on the policy, it may help cover medical bills, court costs, legal expenses, and settlements arising from a covered alcohol-related incident. These protections can be important even when the host is ultimately not found negligent. Defending an alcohol-related claim can generate substantial court costs and legal fees before the case ever reaches trial, leaving an uninsured host with a significant financial burden.

Together, these policies can serve as an important safety net, helping event hosts prepare for both on-site and off-site incidents while creating a more comprehensive risk management strategy.

Event Liability Insurance, COIs, and Additional Insureds

Close-up of an event insurance application being completed, representing the process of obtaining host liquor liability insurance and reviewing coverage details before serving alcohol at a private event.

Most venues require proof that appropriate event liability insurance is in place before allowing an event to proceed, particularly when alcohol will be served. Many commercial venues require a certificate of insurance demonstrating at least $1 million in liability coverage, although the exact minimum depends on the venue contract and event risk. In addition, venues frequently request an additional insured endorsement, naming the venue on the policy to help satisfy contractual insurance requirements. In practical terms, many venues will not allow organizers to open the bar—or even pop the champagne—until the required proof of coverage has been approved.

To avoid last-minute issues, organizers should review venue insurance specifications well in advance and ensure policy effective dates cover the entire event timeline, from setup and vendor arrival through teardown and load-out. Event-specific policies may allow hosts to select the number of days for which coverage is needed, while some insurers offer host liquor liability coverage lasting up to one year. It is also important to confirm any contract-specific provisions, including primary and noncontributory wording, waiver of subrogation requirements, and other venue-mandated endorsements.

Addressing these requirements early can help streamline the approval process, support contractual compliance, and reduce the risk of coverage gaps that could delay or disrupt an event.

Managing Event Liability with Bartenders, Caterers, and Third-Party Alcohol Partners

Bartenders preparing cocktails at a private event, highlighting occasions where alcohol is served by a catering team and organizers may need host liquor liability insurance depending on the event and liquor service arrangements.

Even when an event organizer purchases the alcohol, the responsibility for serving it is often delegated to a venue, caterer, or professional bartending service. Because these third-party alcohol partners typically control alcohol service, staffing levels, guest monitoring, and ID verification procedures, they may also have their own insurance and licensing obligations.

To help clarify responsibilities and reduce potential coverage disputes, event organizers should request and review bartender and caterer COIs early in the planning process, along with any relevant policy documents outlining insurance requirements and responsibilities. These documents can help verify that vendors meet venue liquor insurance requirements and maintain appropriate liability and liquor-related coverage. However, a venue, caterer, or bartending company having its own insurance does not necessarily eliminate the organizer’s need for a separate host liquor liability policy. Each policy protects different parties and activities, so organizers should confirm how the coverages work together rather than assuming a vendor’s insurance provides complete protection.

Organizers should also review any contract provisions that require specific endorsements, such as waiver of subrogation wording, additional insured status, or other insurance obligations. In addition, vendors should be familiar with applicable state laws, including regulations related to alcohol service and underage drinking, as compliance failures can increase liability exposures. Understanding the covered reasons for potential claims and how responsibilities are allocated among parties can help reduce confusion if an incident occurs.

By confirming coverage and responsibilities in advance, event hosts can help ensure accountability remains with the party managing alcohol service while strengthening their overall risk management strategy before guests arrive.

Tastings and Limited-Pour Events: Understanding Coverage Limits

Tastings and limited-pour events are often perceived as lower-risk gatherings, but they still involve many of the same exposures associated with traditional alcohol service. Whether attendees are enjoying free drinks or participating in a structured tasting experience, guests may move between multiple stations, consume several samples over a short period, and experience varying levels of impairment without realizing it.

As a result, organizers should take proactive steps to support both guest safety and risk management. Establishing clear pour sizes, pacing alcohol service throughout the event, providing ample water and food options, and monitoring service areas can help reduce the potential for overconsumption. These precautions are important regardless of whether the event involves hosting alcohol or selling alcohol. Trained staff should also remain attentive to guest behavior and be prepared to limit service when necessary.

Event bar with wine glasses prepared for service, representing catered functions and receptions where understanding host liquor liability insurance is an important part of event risk management.

In addition, maintaining thorough incident reporting for alcohol-related claims can help document response efforts and support a stronger defense if an issue arises. Because most venues have expectations regarding responsible alcohol service, these practices can help organizers meet venue requirements while protecting guests. For small businesses hosting tastings, mixers, or promotional events, implementing thoughtful alcohol management procedures can create a safer experience for attendees while strengthening the defensibility of event operations should a claim occur.

Common Claim Scenarios at Receptions

Receptions and mixers can generate a variety of liability claims, especially when alcohol service is part of the event. Common scenarios include a guest who slips near a bar where a spill has created a hazardous walking surface, an altercation that results in bodily injury or property damage, an accident on a crowded dance floor, or a motor vehicle collision involving an intoxicated guest after leaving the venue. These risks are not limited to corporate receptions and can also affect small weddings and other special events where alcohol is served. In many claims, guest actions and questions surrounding alcohol service practices become key factors in determining liability.

These incidents can lead to significant third-party bodily injury claims, particularly when over-service and intoxication risk are alleged. This is one of the primary reasons venues and insurers treat alcohol exposure as a separate underwriting consideration rather than simply another aspect of general event risk. By understanding these common claim scenarios and securing appropriate reception insurance, event organizers can better manage potential liabilities while demonstrating a proactive commitment to guest safety and responsible alcohol service.

Liability Insurance Limits and When Venues Require More

Guests enjoying wine at a private social gathering, illustrating the type of event where host liquor liability insurance can help protect hosts if alcohol-related incidents lead to third-party injury or property damage claims.

Not all events carry the same level of alcohol-related exposure, which is why some venues impose higher liability requirements for receptions with large guest counts, extended service hours, or late-night activities. For large events, understanding and meeting venue liquor insurance requirements is an important part of the application process, particularly when alcohol service is involved. Event planning and insurance should work hand in hand to address potential risks before guests arrive.

In these situations, organizers should carefully review venue contracts and ensure that coverage limits, endorsements, and supporting documentation, including a certificate of insurance (COI), align with the venue’s specifications. This may include higher limits for Host Liquor Liability For Receptions, additional insured endorsements, or other policy provisions required as a condition of venue approval. By securing appropriate coverage and confirming all insurance requirements well before the event date, hosts can help streamline approvals, avoid last-minute complications, and reduce the likelihood of being held responsible for claims that could have been addressed through proper insurance planning.

Hosts should also remember that liability insurance and event cancellation coverage address different risks. Liability coverage responds to eligible third-party claims, while event cancellation insurance may reimburse certain non-refundable expenses when an event is cancelled or postponed for a covered reason. Ultimately, thoughtful preparation, responsible alcohol service, and properly structured insurance coverage work together to create a safer and more successful event experience for everyone involved.

Sources:

https://acera.ca/host-liquor-liability-everything-you-need-to-know/
https://giffordcarr.ca/blog/host-liquor-liability-insurance/
https://www.covermyconfetti.com/blog/event-insurance-hub-35/event-insurance-coverage-breakdown-62
https://www.reventals.com/blog/what-is-the-difference-between-a-host-bar-and-an-open-bar/
https://www.covermyconfetti.com/special-event-insurance-hosts-only
https://beerrepublic.eu/blogs/news/how-to-host-tastings

When clients ask, “How much does event insurance cost?” they’re rarely seeking a generic number, they’re trying to move forward quickly because venues require proof of coverage before confirming the date or finalizing contracts. In special event insurance, whether for a business function, wedding, birthday party, baby shower, family reunion, corporate dinner, or sporting event, this is where the conversation shifts: the real focus isn’t just cost, it’s placement. Experienced brokers understand that pricing questions signal urgency and a need for clarity, not just budget sensitivity.

For brokers, event insurance for brokers is ultimately about translating urgency into a clean placement strategy that satisfies the venue, fits the exposure, and gives the client confidence before the event moves forward. By using a structured approach and translating key event details, such as attendance, activities, location, and risk profile, into clean underwriting inputs, brokers can deliver fast, accurate quotes that satisfy venue requirements without unnecessary coverage.

Ultimately, the value of special event insurance isn’t defined by the lowest price, but by how efficiently and confidently the policy fits the event. Timing also matters. Many venues require proof of event insurance from the event host before confirming the date, and some require proof of insurance at least 30 days before the event. That means a pricing question often reflects a documentation deadline, not simply a request to compare premiums.

The Three Event Insurance Cost Drivers Underwriters Price First

When underwriters evaluate a submission, pricing is typically anchored to three primary drivers: event type, headcount, and event location, core event insurance underwriting factors that define the overall risk profile. Details like headcount and attendance rating signal the scale of potential exposure, while the nature of the event, whether small gatherings or large corporate events, helps determine the likelihood of incidents such as bodily injury or property damage, along with associated legal fees that may arise from claims.

From there, underwriters look at the requested coverage limits. For example, liability limits for event insurance may start at $500,000, and many venues require proof of liability insurance with limits of $500,000 or more. As limits increase, pricing can change quickly, especially when the contract requires specific wording or additional insured status. This is also why relying on a standard homeowners or renters insurance policy can create problems. Those policies often exclude off-site events or provide lower liability limits than a dedicated event liability insurance policy, which can leave clients short of what the venue requires.

For example, a small, private gathering in a controlled setting generally presents less risk than a large, public-facing event held in a high-traffic downtown location. These differences directly influence how each insurance policy is priced and structured, as insurance can help protect against financial loss tied to injuries, damages, and defense costs. Understanding how these elements shape underwriting allows brokers to position submissions more effectively, resulting in faster, more accurate quotes that align with both client expectations and venue requirements.

Event Liability Limits That Match Venue Contracts Without Overbuying

Signed contract and event documentation, emphasizing the agreements, venue requirements, and insurance certificates that brokers often help clients navigate before an event takes place

When it comes to pricing, event liability coverage limits are often less about risk alone and more about meeting venue contract insurance requirements, something event planners encounter regularly, especially when clients look to buy event insurance for larger events. Many venues specify minimum limits and require exact certificate wording, which can influence premiums more than the event details themselves.

Many venues set minimum liability requirements, often starting at $500,000 or more, and may not approve the event until the certificate reflects those limits exactly. The key for brokers is to align coverage precisely with these requirements, working closely with insurance carriers to ensure each policy is structured to both comply and effectively cover claims without defaulting to unnecessarily high limits.

This also helps clients make informed decisions when considering additional protections, such as event cancellation insurance, based on their financial exposure. By matching coverage to contract language and only increasing limits when a venue or municipality explicitly requires it, brokers help clients avoid overbuying while still achieving fast approval and seamless contract execution.

Event Insurance COIs, Additional Insureds, and Why Wording Affects Price

Attendees networking at a social or corporate function, highlighting the wide range of events that may require liability protection and the importance of brokers matching coverage to the event’s size and activities

Certificates and endorsements can have a bigger impact on pricing and turnaround than many expect, especially depending on the type of event and the parties involved.

While adding additional insureds is standard practice, the specific wording required in contracts can determine who may be held responsible in the event of a claim and how the policy responds.

Seemingly small details, like primary and noncontributory language or a waiver of subrogation, may require adjustments that affect the final premium and how the certificate of insurance (COI) is issued.

These elements also clarify what the event insurance cover includes, including how the policy responds if a guest slips and is injured, or if accidental property damage occurs at the venue. A well-prepared COI package that aligns with vendor and venue requirements reduces back-and-forth, minimizes last-minute revisions, and avoids delays or re-rating. For brokers, getting the wording right the first time not only streamlines placement but also builds confidence with clients and venue partners alike. This is also where brokers can answer the practical question clients are really asking: what does event insurance cover, and does the certificate prove that coverage in the way the venue expects?

Liability Versus Event Cancellation: Separating Two Different Budgets

When discussing insurance coverage, it’s essential to separate liability from cancellation, as they address entirely different exposures and require distinct budget considerations, something event planners must carefully manage. Liability coverage is driven by the risk of third-party injury or property damage, while event cancellation coverage focuses on the client’s financial investment, including sunk costs, vendor deposits, planning expenses, and risks like extreme weather that can disrupt, postpone, or cancel an event.

Timing is especially important for cancellation coverage. Brokers should advise clients to consider purchasing insurance as soon as they begin paying initial deposits, because event cancellation insurance typically requires advance purchase and may need to be bought at least 14 days before the event. Event cancellation insurance can help reimburse lost deposits and non-refundable amounts if the event is cancelled or postponed due to covered unforeseen circumstances. However, cancellation insurance is not open-ended, and some losses may be excluded depending on the policy.

Because these coverage options are priced based on different factors, brokers can help clients stay cost-efficient by prioritizing the most immediate need, typically liability for venue compliance, before layering in cancellation only when there is significant non-refundable exposure at stake. Thoughtful deductible and limit decisions across each line of insurance coverage further refine pricing, helping clients balance meaningful protection with affordability while avoiding paying for coverage they don’t yet need.

Big Event Alcohol, Vendors, And Exhibitors: The Fastest Ways Cost Changes

Alcohol, vendors, and exhibitors can quickly shift an event’s risk profile, and pricing, based on several factors that influence overall exposure. Serving alcohol, even on a hosted basis, introduces added risk and often requires host liquor liability or liquor liability insurance, which helps cover claims related to alcohol-related incidents, including medical bills, medical expenses, and property damage. This added exposure can increase premiums due to the higher likelihood of injury-related claims. Bringing in third parties, such as vendors, food trucks, or exhibitors, adds further complexity, as responsibility is shared and coverage must extend across multiple participants.

Guests being served wine at a private gathering, representing events where brokers may help clients secure appropriate event liability coverage, including options related to alcohol service exposures

If the event includes an open bar or BYOB arrangement, liquor liability coverage may be included in the event insurance cost or added as a required coverage option, depending on the carrier and event details. Vendor-heavy events like markets, trade shows, and brand activations require careful coordination of COIs and clear allocation of risk, with each element shaping how the policy is structured. For brokers, understanding these several factors early ensures the insurance program is built to accurately reflect exposures, helps cover potential claims effectively, and avoids surprises during underwriting or venue approval. For vendor-heavy events, brokers should also confirm whether each vendor is carrying its own coverage. That helps prevent the host’s event liability coverage from being treated as the first line of response for every claim connected to the event.

Day Event Deductibles, Umbrellas, and When Higher Limits Make Sense

Deductibles and excess layers play a key role in shaping both pricing and practicality, making thoughtful choices essential in structuring liability insurance for events and other special events. Even a modest adjustment in deductible can reduce premium, but it should reflect what the client can realistically afford to absorb if a claim arises on short notice.

These decisions directly impact how the policy may cover losses, ensuring the insurance may cover claims in a way that aligns with the client’s financial comfort level. At the same time, when venue contract requirements call for higher limits than standard event liability insurance policies provide, adding an umbrella is often the most efficient solution. This approach allows brokers to extend liability insurance cleanly and cost-effectively, ensuring compliance with higher limits while maintaining a streamlined base policy that continues to protect the event appropriately.

A Broker-Ready Intake with Coverage Limits That Produces Faster Quotes

A streamlined intake is what turns urgency into efficiency, especially when placing liability policies for everything from one-day functions to multiple day events. By following a clear broker placement checklist and capturing essential details, event date(s), venue address, headcount, alcohol plans, vendor participation, and any special activities, brokers create a concise snapshot built around key underwriting factors that underwriters can quickly evaluate.

The intake should also account for timing. Event liability coverage may need to be purchased at least one day before the event, while planned events can often be insured up to two years in advance. Short-term event insurance may also be available for events with fewer than 12,000 attendees and durations of up to 10 days, depending on the carrier.

This approach minimizes back-and-forth, accelerates pricing, and allows for easy comparison across coverage options, including those that address risks like lost deposits and planning expenses. With clean, complete inputs from the start, brokers can explain tradeoffs clearly and place coverage that satisfies venue requirements on the first pass, delivering both speed and confidence when it matters most.

Real estate professional conducting a property walkthrough with prospective buyers, illustrating the role brokers play in helping clients understand property-related risks and insurance considerations

Sources:

https://harvardwestern.com/trade-show-exhibitor-insurance/
https://brite.co/blog/how-to-get-wedding-insurance/
https://acera.ca/event-insurance-what-you-need-to-know/
https://esportsinsurance.com/special-event-insurance-brokers-guide/
https://www.dulibaninsurance.com/blog/what-do-insurance-brokers-do/
https://eventsguardian.com/event-insurance-broker/

When it comes to insuring single-date events, the conversation is fundamentally different, especially when special event insurance is being used to satisfy specific venue insurance requirements. Rather than relying on a broader annual policy, organizers often need event liability coverage that is tailored to the date, location, guest count, and risk profile of the event. Unlike ongoing operations, these events compress risk into a narrow, high-intensity window, where setup, peak activity, and teardown all happen in quick succession.

That concentrated exposure demands a more precise approach rather than a one-size-fits-all annual policy. A properly structured policy can provide coverage that aligns with the timing, scale, and unique exposures of the event, giving brokers a practical way to secure venue-ready protection while ensuring clients are covered without committing to unnecessary long-term insurance.

What One-Day Event Liability Insurance Typically Covers

At its core, One-Day Event Liability Insurance is built around general liability insurance, focusing on the most immediate exposures tied to a single event, namely, third-party bodily injury and third-party property damage that occur during the defined event window. This includes common, real-world scenarios such as a guest slipping and falling during peak attendance, resulting in medical bills, or accidental damage to a venue’s floors, walls, or fixtures during setup or teardown. In these situations, event insurance cover can help address expenses that would otherwise fall directly on the organizer.

Because organizers can be held responsible for these incidents, especially when venues require proof of adequate protection, this type of coverage is designed to address these time-specific risks. Ultimately, it helps ensure that both event organizers and venues are financially protected from unexpected incidents that can arise before, during, or immediately after the event.

The COI and Additional Insured Requirements for Big Events: What Venues Expect

When it comes to satisfying venue insurance requirements, the certificate of insurance (COI) and additional insured endorsement are often non-negotiable details that can make or break event logistics, especially for larger gatherings where capacity limits or a maximum number of attendees are enforced. Most venues require a COI that clearly names them as an additional insured, with coverage limits and policy dates that align precisely with the event schedule and coordination with other vendors involved.

Even small discrepancies, such as incorrect wording or a policy period that fails to include load-in and strike, can lead to last-minute access issues that disrupt set up, create scheduling conflicts, or even result in lost deposits. This is also where speed matters. In many cases, organizers can buy event insurance online in just a few minutes, complete payment, and receive a certificate of insurance shortly afterward as proof of coverage. For straightforward events, coverage may be available immediately upon completion of the application, which can be especially valuable when venue access depends on having the correct documents in hand. Ensuring accuracy and completeness upfront is essential to keeping all moving parts aligned and avoiding costly disruptions at critical moments.

Event registration or liability waiver form being completed before an activity or gathering, emphasizing the planning and documentation often involved in event risk management

Damage To Premises Rented to You: The Contract Trigger

For many one-day rentals, coverage discussions often come down to a specific policy requirement written directly into the venue contract, particularly the ability to respond to accidental damage to the rented space. This detail can have real implications for an event organizer’s business, especially when venues tie damage responsibility to financial outcomes such as retaining or issuing a full refund of security deposits.

In these situations, organizers can be expected to protect the venue from losses during occupancy, making it critical that coverage aligns with those contractual terms. Without the right policy in place, even minor incidents, like spills, equipment mishaps, or décor-related damage, can quickly escalate into out-of-pocket costs and disputes that extend beyond the event itself. A clear policy structure can also support an easier claims process by showing what coverage applies, when the event was insured, and which parties were included under the policy.

How Host Liquor Liability Impacts Risk at a One-Day Event

Beverage service at an outdoor event, representing the importance of managing guest safety and understanding potential risks associated with serving refreshments at special occasions

Alcohol service can significantly shift the risk profile of a one-day event, even when it’s informal or limited in scope. The presence of alcoholic beverages increases the likelihood that an accident may occur, from guest injuries to property damage, and often leads venues to impose stricter venue insurance requirements.

In these situations, host liquor liability becomes an essential safeguard and a common solution for organizers who do not sell alcohol but may still purchase and provide it, making them responsible for the event environment. If liquor liability coverage is added, event insurance may provide coverage for damages or injuries arising out of alcohol-related incidents, subject to policy terms and exclusions. Without this layer of protection, a single alcohol-related claim can escalate quickly, exposing organizers to financial and legal risks that extend well beyond the event itself.

Vendors, Contractors, and Shared Responsibility

Vendors, contractors, and third-party service providers can introduce layers of exposure that don’t always stay contained to their individual roles, especially at larger functions like trade shows, where coordination is more complex and stakes are higher. Pop-up vendors, caterers, entertainers, and rental companies all interact with guests and the venue, which means any misstep, whether it’s food-related illness, equipment damage, or injury, can directly impact the organizer’s overall coverage and financial responsibility.

It is also important to clarify who is actually covered by the policy. Standard event liability coverage is generally designed for third-party claims and may not cover injuries to an active participant, performer, sporting participant, or individual compensated by the insured. For events involving demonstrations, performances, athletic activity, or paid participants, this distinction should be reviewed carefully before the event date.

Because many venues require clear proof that each party is properly insured, a structured approach becomes essential. Requiring vendor liability policies and collecting certificates of insurance (COIs) helps ensure accountability stays with the party performing the work, ultimately protecting the organizer from unnecessary risk and potential loss of money tied to claims or disputes.

Event attendees networking and greeting one another at a professional function, illustrating the liability considerations that come with hosting meetings, conferences, and corporate events

When Event Cancellation Coverage Becomes Part of the Conversation

While event liability coverage is focused on injury and property damage claims, event cancellation coverage addresses a different concern: what happens if the event cannot proceed as planned. For weddings, fundraisers, concerts, conferences, and other special events with significant upfront expenses, event cancellation insurance can help protect against certain financial losses tied to cancellation, postponement, or interruption.

This is especially relevant when more than half of the event budget has already been committed to deposits, vendor payments, venue costs, or non-refundable arrangements. Covered reasons vary by policy, but cancellation coverage may respond to certain unforeseen circumstances, including extreme weather or venue-related issues, depending on the terms of the policy.

However, cancellation insurance is not unlimited. Event cancellation insurance typically does not cover every cause of loss, and many policies exclude losses arising from infectious diseases, including pandemics. For brokers, the key is to separate the liability conversation from the event cancellation conversation so clients understand what each policy is designed to protect.

Limits, Umbrellas, and When “Standard” Isn’t Enough

When it comes to special event insurance limits, what’s considered “standard” for a one-day event doesn’t always meet the requirements set by venues or local municipalities, especially when higher limits are mandated through an additional insured endorsement. Many standard policies may offer limits up to $1 million or $2 million per occurrence, but larger crowds, higher-risk activities, or unique event elements can create exposures that exceed basic policy thresholds. Larger crowds, higher-risk activities, or unique event elements can increase exposure and create the potential for unforeseen circumstances that exceed basic policy thresholds.

In these cases, an umbrella policy becomes a practical way to protect organizers by adding an extra layer of coverage that can help pay for claims once underlying limits are exhausted. This approach allows event hosts to meet elevated requirements while maintaining a streamlined and effective insurance strategy. Depending on the event, specialized protections may also be added to the policy, such as cancellation/interruption coverage or hired and non-owned auto coverage.

What Drives Pricing and Eligibility

Pricing and eligibility for one day event insurance are shaped by a range of practical underwriting factors, including attendance size, venue type, planned activities, alcohol service, and alignment with venue insurance requirements. These elements influence not only how easy it is to purchase coverage, but also the overall cost and terms tied to event liability. Smaller, private gatherings typically present lower risk, while larger or public-facing events introduce variables that can impact pricing and the need to pay higher premiums.

Additionally, if an event must be postponed or cancel plans change, those factors can further complicate coverage decisions. As complexity increases with elevated hazards or unique venue demands, underwriting becomes more detailed, ensuring the policy properly reflects the level of exposure involved. Some providers also allow organizers to bundle event liability coverage with event cancellation coverage, which may create additional savings compared with purchasing the coverages separately.

Buffet table prepared for a one-day event, highlighting the food service exposures that event liability insurance can help address when hosting private gatherings, receptions, or celebrations

Common Claim Scenarios That Make the Coverage “Real”

Many one-day event claims stem from everyday mishaps that can quickly turn into real financial exposures, which is exactly what special event insurance, often structured as part of a general liability policy, is designed to address. A guest slipping near an entrance, a rented chair causing damage to a venue’s floor, or a rushed teardown leading to injury are all common scenarios that can result in costly claims, similar to risks seen in other special events.

These situations may also require additional coverage depending on the event’s scope and venue requirements. While these incidents aren’t unusual, they highlight why venues consistently require proof of liability coverage before granting access, ensuring there is a clear and reliable way to handle damages without delay or dispute.

Sources:

https://www.covermyconfetti.com/blog/event-insurance-hub-35/oneday-event-insurance-guide-63
https://agspecialtyinsurance.com/news/insurance-for-an-event/
https://www.insurancecanopy.com/blog/the-real-cost-of-one-day-vendor-insurance
https://www.abcweddingplanners.com/notebook/blog/the-importance-of-event-liability-insurance
https://www.legalshield.com/blog/why-you-need-event-insurance
https://www.landsagency.com/blog/should-you-add-umbrella-insurance-to-your-one-day-event-insurance-policy/
https://www.statewideslc.com/blog/do-you-need-liquor-liability-insurance-for-a-one-day-event/

Charity galas and auctions bring together multiple risk elements in a compressed timeframe, large crowds, formal venues, alcohol service, and high‑value auction items, making event insurance coverage essential for well‑planned special events. This combination creates exposures that standard policies often don’t adequately address, especially when detailed coordination and logistics amplify event details and potential liabilities. The cost of event insurance can vary based on the coverage limits, venue requirements, event size, alcohol service, and optional coverages selected.

Insurance for Charity Galas is designed to protect the nonprofit, the venue, and attendees from claims that could otherwise derail the event’s purpose. By incorporating tailored nonprofit fundraiser insurance, gala liability insurance, and comprehensive event insurance coverage aligned with specific event details, organizers can safeguard their special events and ensure that a single accident, injury, or property loss doesn’t undo months of planning or compromise fundraising results. Event insurance can also help protect the organization from unforeseen circumstances such as accidents, illness, vendor issues, or disruptions that affect the event’s finances or operations.

Core Event Liability for Receptions and Guest Safety

Guest safety is central to any successful fundraiser, making event liability insurance the cornerstone of gala insurance planning. This type of coverage is essential for many venues hosting formal events and helps address risks arising from unforeseen circumstances. It responds to third‑party bodily injury and property damage claims, such as slips on dance floors, congestion at coat check or registration areas, or décor installations causing damage to premises rented to you, including floors, walls, or fixtures. It may also help cover legal costs associated with claims made against the event host, depending on the terms and conditions of the policy. Organizations should carefully purchase coverage that aligns with the unique risks present at their event.

Because galas concentrate people, activity, and movement into a short period, limits for event liability insurance should be tailored based on attendance size, venue requirements, contract terms, and the realities of many venues where layouts and risks vary. Accounting for unforeseen circumstances in higher‑traffic zones like bar lines, auction tables, and check‑in areas ensures that when planners purchase coverage, they are fully protected against the dynamic exposures common at large fundraising events. Special event insurance is typically written on an occurrence-based general liability form for the dates of the event, making it important to confirm that setup, the event itself, and teardown are properly reflected in the policy period.

Host Liquor Liability and Bar Service Rules

When alcohol is served, host liquor liability insurance becomes a critical component of risk management, especially as many venues require proof of appropriate coverage before an event can proceed. For charity galas, this is especially important because general liability insurance often needs to be paired with host liquor liability when alcoholic beverages are served. This coverage helps address claims tied to intoxication‑related incidents involving alcoholic beverages, including injuries or property damage caused by guests who have consumed alcohol. Having clear policy paperwork in place ensures organizers can demonstrate compliance and secure necessary approvals.

Bartender serving wine at a formal fundraising event where liquor liability insurance may be important

Coverage should be aligned with venue contracts, bar service formats (open bar, drink tickets, or cash bar), and any requirements where venues require proof of insurance and additional insured status. Maintaining accurate policy documents is essential for meeting these obligations. Just as important, organizers must ensure bartending staff, alcohol service procedures, and ID‑verification practices comply with local regulations when serving alcoholic beverages, helping reduce preventable liability exposures. Organizers should carefully review the terms and conditions of any insurance quotation to confirm whether liquor-related claims are included, excluded, or available only through an added coverage option.

Venues, COIs, and Additional Insured Coverage Options

Venue insurance requirements are often among the most time‑sensitive aspects of gala planning, and an event policy must be carefully structured to meet them. After purchasing coverage, organizers typically receive a certificate of insurance (COI) as proof of coverage, which can be shared with the venue, property manager, or other requesting party. Most venues require the COI name them as an additional insured, and many also specify minimum liability limits, required endorsements, or coverage dates spanning setup, the event itself, and teardown.

Meeting venue additional insured requirements often depends on precise wording within the event policy, including primary and noncontributory language, waivers of subrogation, or specific liability limits. Since coverage varies across insurers and event types, careful review ensures compliance with what most venues mandate. Confirming these details early helps avoid last‑minute approval problems that can delay load‑in, limit vendor access, or jeopardize the venue’s final authorization. While event insurance can often be arranged close to the event date, organizers are usually better served by securing coverage as soon as the venue contract is signed so there is time to review requirements, correct certificate wording, and amend the policy if event details change.

Silent Auctions, Raffles, and Prize Exposures

Silent auctions and raffles at a big event introduce distinct exposures related to item handling, display, and guest movement. High‑value items may be transferred multiple times, increasing the risk of damage, loss, or disputes, especially in crowded auction areas where an insurance company may later evaluate how risks were managed.

Charity raffle or silent auction drawing during a fundraising gala event with guest participation

Silent auction insurance and coverage addressing raffle and prize liability help protect the organization if donated items are lost, damaged, or subject to a claim. For any big event, establishing clear procedures for display, secure storage, checkout, and pickup is essential. In addition, working closely with an insurance company and maintaining documented incident reporting and claims handling processes helps protect the organization and supports efficient resolution if an issue arises. Event insurance policies can often be customized with optional coverages based on the specific needs of the event, including exposures related to high-value auction items, raffles, guest participation, or vendor activity.

Event Insurance for Vendors, Caterers, and Entertainment Partners

Third‑party vendors are essential to gala success, but they also introduce additional liabilities that can extend to the event organizer, making it important to understand how vendor activity affects the overall insurance structure. Caterers, bartenders, AV teams, and entertainers may carry their own coverage, yet injuries or property damage connected to their services can still trigger claims under the organizer’s event general liability or broader special event coverage.

Collecting vendor and caterer COIs confirms active coverage and appropriate limits, while contracts should clearly assign responsibility for damage to venue property, rented equipment, or décor tied to hired venue and banquet hall coverage. Working with reputable insurance companies and evaluating how much does event exposure vary by vendor type helps ensure adequate special event coverage. Addressing these details in advance reduces disputes during setup, the event, or teardown. Event insurance can cover a variety of events, including weddings, corporate gatherings, community fundraisers, auctions, and charity galas, but the right coverage mix depends on how the event is actually structured.

Elegant charity gala dinner setup with banquet tables, lighting, and formal event venue staging

Holiday Events: Weather Challenges and Cancellation Insurance

Gala timing, especially during the holiday season, adds another layer of uncertainty, with medical expenses and property damage arising possible when conditions become unpredictable. Winter storms, travel disruptions, or last‑minute venue issues can force a cancellation or postponement, triggering lost deposits, rebooking fees, and vendor expenses that may quickly exceed planned coverage limits. Event cancellation insurance can help reimburse certain lost deposits and expenses if a charity gala is canceled or postponed due to covered unforeseen circumstances.

Event cancellation and postponement protection, including cancellation coverage for weather-related disruptions, vendor failure, accident, illness, or other covered circumstances, helps protect prepaid commitments when circumstances are outside the organization’s control. Establishing appropriate coverage limits within a comprehensive policy ensures financial safeguards align with potential losses, including medical expenses and property damage arising from unforeseen incidents. Securing this protection as part of a broader holiday gala insurance strategy gives stakeholders confidence that key investments are protected, even when unexpected disruptions occur.

When to Arrange Event Insurance for a Charity Gala

Event insurance can often be arranged close to the event date, but waiting until the last minute can create unnecessary pressure. Venue contracts, certificate wording, additional insured requirements, alcohol service, vendor documents, and setup schedules may all need to be reviewed before the event is approved.

A better approach is to arrange coverage as soon as the venue contract is signed. This gives organizers time to review the quotation, confirm the terms and conditions, secure the certificate of insurance, and make amendments if event details change.

Making Event Insurance Work: Choosing the Right Limits, Dates, and Deductibles

Selecting the right insurance structure comes down to aligning an event’s own insurance with the real‑world risks it presents. For larger, higher-profile, or contractually demanding events, an umbrella policy may provide additional liability limits above the underlying event policy. Organizers should evaluate coverage options that reflect guest count, venue mandates, alcohol exposure, and the presence of high‑value auction or raffle items, especially for multi day events where exposures extend over longer periods.

Policy effective dates must also satisfy COI requirements by extending beyond event hours to include load‑in, rehearsals, and teardown, times when incidents are more likely to occur and policies may need to cover claim activity. Short-term event insurance can provide liability coverage for temporary events, including fundraisers, receptions, auctions, and other gatherings held over a defined event period. Some facilities may also offer or require a Tenant User Liability Insurance Policy, commonly known as TULIP, which provides short-term liability insurance for third parties using a facility for a specific event.

Event organizer reviewing charity gala plans, insurance documents, and vendor communications on a mobile device

Finally, deductibles should align with the nonprofit’s realistic out‑of‑pocket tolerance. Reviewing coverage options carefully ensures the organization’s insurance is structured to respond effectively and cover claim scenarios without financial strain. If event details change, such as guest count, alcohol service, venue requirements, vendor participation, or setup schedule, the policy should be reviewed and amended as needed to keep coverage aligned with the actual event. When properly designed for single or multi day events, nonprofit fundraiser insurance supports fundraising success rather than becoming a last‑minute obstacle. For nonprofit fundraisers, organizers may also want to review Volunteer Liability or Volunteer Accident Insurance for injuries involving volunteers, as well as Directors and Officers Liability for board-level claims involving alleged mismanagement or wrongful acts.

Sources:

https://giffordcarr.ca/blog/host-liquor-liability-insurance/
https://www.phly.com/blog/non-profit-special-event-insurance
https://www.bfsaulinsurance.com/blog/how-much-insurance-do-i-need-to-cover-my-nonprofit-event
https://eventsguardian.com/liquor-liability-insurance-for-event/
https://alkemeins.com/blog/understanding-event-insurance-for-nonprofit-fundraisers
https://westernfinancialgroup.ca/Protect-Your-Cause-with-Fundraising-Insurance
https://www.moorehemsworth.ca/blog/special-event-insurance-during-the-holidays

Fashion events are a unique category of special events, operating under intense time pressure and high visibility that few other productions encounter. A runway show brings together talent, custom staging, intricate lighting, high‑value garments, VIP guests, media, and sponsors, all within a compressed window where timing is critical and there is little room for error.

With so many moving parts and stakeholders involved, even minor issues, like a delayed cue, technical malfunction, or on‑site disruption, can quickly escalate into significant liability claims, especially when unforeseen circumstances arise. This is where event insurance, including specialized fashion show and liability coverage, becomes essential. Rather than serving as a last resort, insurance functions as a proactive risk management tool, helping organizers, venues, and partners maintain stability and protection when conditions shift rapidly and potential exposures increase.

Special event insurance is a short-term liability policy designed to help protect event hosts from financial losses tied to accidents, injuries, property damage, or other covered incidents during the approved event period. The application process can often be completed online or through a formal enrollment form, allowing organizers to request quotes, submit event details, and secure proof of coverage documents with minimal delay.

The Venue Comes First: Insurance Coverage, Contracts, COIs, and Access

In fashion production, venue requirements often determine not just what can move forward, but when. Most venues will not finalize load-in schedules, rehearsals, or guest access until they receive a compliant venue certificate of insurance (COI) from an insurance provider, clearly outlining event dates, coverage limits, additional insured status, and contract-specific wording. Event insurance policies often allow additional insured parties, such as the event venue, sponsors, or certain vendors, to be added when required by contract. This helps extend liability protection to those parties for covered claims connected to the event.

Securing an additional insured endorsement early, while ensuring limits address exposures such as bodily injury, property damage, and even potential legal fees, helps avoid bottlenecks that can disrupt production timelines. When insurance documentation is properly aligned with venue agreements from the outset, organizers significantly reduce the risk of last‑minute disputes, keeping operations smooth, crews coordinated, and the event on track for showtime. Venues increasingly ask for specific endorsements, wording, and coverage details, making it important to review the contract before binding coverage. The effective date of coverage should also reflect when the event exposure actually begins, including setup and teardown when required. Because documentation can take time to review and revise, organizers are usually better served by purchasing coverage early in the planning process rather than waiting until production details are already locked.

Event Details in Focus: Staging, Lighting, and Temporary Build Exposures

Runway staging delivers powerful visual impact, but it also introduces some of the highest‑risk exposures present at most events, particularly those involving complex professional services like production design and technical installation. Temporary runways, truss systems, risers, and lighting rigs create real potential for property damage and bodily injury throughout load‑in, rehearsal, live production, and strike, making hired equipment and staging coverage a core element of a comprehensive risk strategy. Personal property and equipment coverage may also be important when expensive sound systems, lighting equipment, rented staging, production gear, or other high-value event materials are being used on site.

At many venues, accelerated build schedules, limited backstage space, and multiple vendors working simultaneously increase exposure to temporary structures and rigging liability. Coverage must account not only for showtime conditions, but also for the realities of fast‑paced installs and breakdowns. Property damage liability, for example, can also help address situations where the organizer, vendor, or production activity causes damage to someone else’s property during the event period. Pairing appropriate limits and policies with clear incident reporting and claims handling procedures ensures protection extends across every phase of production, especially in high‑pressure environments where timing is tight and risks can escalate quickly.

Guests, Seating, and High-Footfall Event Liability

Empty runway and seating layout before a fashion event begins, suitable for venue preparation, staging, and event setup discussions

Guest experience is central to a successful fashion show, but it also introduces consistent exposure that must be managed within strict insurance requirements and venue compliance standards. Front‑row seating, crowded check‑in areas, narrow aisles, and compressed arrival windows create ideal conditions for slips, trips, and falls, common risks addressed under event general liability for fashion shows and broader contractual liability obligations outlined in venue agreements. Common accidents at fashion events might include bodily injury from trips and falls, property damage to the venue, and liability issues tied to crowded entrances, seating areas, media zones, or reception spaces.

These exposures intensify when VIP arrivals, media presence, and tight call times funnel large groups through limited access points. Effective planning requires aligning liability insurance limits with attendance, layout, venue requirements, coverage limits, location, event type, and any previous claims history that may affect underwriting. Incorporating proper event security and crowd control liability ensures coverage reflects how guests actually move through the space, not just how many attend, helping organizers manage risk in line with both operational realities and contractual obligations.

Backstage Control and Insurance for Fashion Events: Talent, Staff, and Restricted Areas

Backstage at an event venue functions as a high‑risk environment, distinct from the polished, public‑facing runway. Rapid outfit changes, exposed cables, mirrors, styling tools, and constant foot traffic all increase the likelihood of injury or equipment damage, making strong backstage access controls essential. These conditions can lead to third party claims if incidents impact talent, crew, or visiting media. This is especially important in backstage environments where models, stylists, dressers, production staff, and media may be moving quickly through tight spaces with limited visibility and little margin for error.

With models, stylists, production teams, and press often operating in shared, confined spaces, clearly defined roles and controlled access help reduce confusion and unauthorized entry. At the same time, model and talent liability considerations become more complex as individuals work under pressure in tight conditions. Even with well‑structured protocols, incidents can still occur, making coverage from an insurance company, supported by clear incident reporting and claims handling procedures, a critical safeguard that complements operational planning and helps manage backstage risk effectively.

Fashion show production team coordinating backstage with models, styling, and event logistics before runway launch

Vendors, Sponsors, Production Partners, and Additional Insured Requirements

Fashion shows and other business events rely on a broad ecosystem of third parties, from AV teams and decorators to security personnel, bartenders, photographers, and brand sponsors running on‑site activations. Each vendor introduces its own operational risk, making it essential for event organizers to collect vendor and contractor COIs well in advance and verify proper coverage. Vendor contracts generally require caterers, tech crews, AV providers, security teams, and other production partners to carry their own insurance so the organizer is not left absorbing coverage gaps created by third-party work.

Strong agreements with clearly defined roles, supported by contract and indemnification clauses and the right additional insured coverage, help ensure accountability is properly assigned if a claim occurs. When coverage aligns with contractual responsibilities, event organizers reduce the likelihood of absorbing losses caused by third‑party actions and minimize costly coverage gaps during live production. In some cases, additional insured endorsements may be available as part of the policy structure, though more complex wording or unusual contractual requirements may require extra review by the insurance provider.

Samples, Wardrobe, and Brand Assets on Site

Wardrobe samples, accessories, and branded display pieces are often among the most valuable, and least replaceable, assets at a fashion event, regardless of the event type. In many cases, venues require proof of proper coverage to ensure these high‑value items are protected, making wardrobe and sample inventory coverage a critical consideration, especially when pieces are one‑of‑a‑kind and needed on tight timelines.

Clothing racks and wardrobe preparation backstage before a fashion show, useful for discussing designer garments, inventory, and vendor-related exposures

From transport and fittings to backstage handling and post‑show load‑out, these assets face ongoing exposure to loss, damage, or unexpected incidents. Unattended racks, shared staging areas, and rushed breakdowns increase vulnerability, particularly when combined with hired equipment and staging risks. Implementing clear asset tracking, along with structured incident reporting and claims handling procedures, helps ensure any issues are addressed quickly and effectively, protecting valuable items from arrival through final strike. Because standard policies may not automatically protect garments, samples, or inventory in every scenario, organizers should review exclusions carefully before assuming these assets are covered.

Managing Security, Media, and Filming Permissions Under General Liability Coverage

Media presence can significantly elevate risk at an event if not carefully managed, making event liability considerations even more critical. Camera crews, lighting stands, and cable runs introduce trip hazards, while photo calls and branded backdrops often create sudden crowd surges that impact overall safety and crowd control. Many venues and partners also require proof of insurance before media access is granted, reinforcing the need to properly purchase coverage that accounts for these exposures.

Conflicts may arise when photographers or content creators move beyond approved zones or fail to follow established filming permissions. Strong security planning, credential control, and clearly defined filming areas support effective backstage access management, helping organizers maintain order, protect restricted spaces, and reduce the likelihood of liability issues if incidents or disputes occur. Organizers should seek policies tailored to special events because fashion shows involve a different risk profile than a standard reception, meeting, or private gathering.

Attendees recording a runway presentation on smartphones during a fashion event, highlighting media exposure and crowd-related event risks

Receptions and After-Parties: Host Liquor and Crowd Dynamics

Post‑show receptions or after‑parties can quickly change the risk profile of special events, particularly when alcohol service is introduced. Increased activity around bar lines, dance floors, stairways, and exits heightens the likelihood of claims arising from slips, altercations, or injuries, making both event general liability and liquor liability coverage essential considerations. Liquor liability coverage is essential for fashion events where alcohol is served because it helps protect against claims related to intoxicated attendees.

As crowd movement becomes less structured, exposures grow, and risk management must align closely with the terms outlined in the venue contract. Whether alcohol service is handled by the venue, a licensed caterer, or the organizer, clearly defined responsibilities and appropriate coverage help ensure liability is properly addressed. Coordinating crowd dynamics with service flow, supported by adequate liquor liability coverage, allows event organizers to balance guest experience with proactive protection against potential claims. Organizers should confirm whether liquor liability is included, excluded, or available as an added coverage option, especially when alcohol service is handled by a caterer, sponsor, venue, or third-party bar provider.

Event Cancellation, Postponement, and Reputation Pressure

Fashion runway show with seated audience and professional lighting, ideal for illustrating large-scale fashion event production and liability considerations

Fashion calendars leave little room for error, and when disruption occurs, the impact extends far beyond immediate financial loss. Venue issues, talent no‑shows, weather events, or production failures can prevent the event held from moving forward, triggering non‑refundable deposits, sunk costs, and sponsor obligations. These scenarios highlight critical insurance needs, where cancellation coverage becomes essential to help offset losses and protect invested resources.

Ensuring the right protections are in place requires careful review of policy documents, along with clear contract and indemnification language that defines financial responsibilities. Beyond direct costs, reputational pressure from designers, brands, and media can intensify the impact. Well‑structured fashion show insurance, supported by comprehensive cancellation coverage, provides the financial protection and flexibility organizers need when unforeseen circumstances make it impossible to execute the event as planned.

Sources:

https://www.linkedin.com/pulse/legal-side-fashion-shows-what-designers-must-secure-before-akwaboah-zvk5e/
https://sceptreprotection.com/operations/event-security-at-international-fashion-show/
https://yourfashionlawguide.com/2025/07/01/before-the-heels-hit-the-runway-the-fashion-show-legal-checklist/
https://nikonikoevents.com/runway-ready-strategies-for-a-seamless-fashion-show-experience/
https://www.mdpi.com/2075-471X/8/4/29
https://dcfashionweek.org/the-ultimate-guide-to-planning-a-fashion-event/

Universities, departments, student organizations, and third‑party groups assume risk as soon as they place an event on the campus calendar, and that risk extends across lectures, performances, campus traditions, and other special events. From guest speakers and club fairs to large public gatherings, even well‑planned programs can create exposure for injuries, property damage, or contractual disputes.

Purchasing insurance with the right event coverage, including campus, university, and student organization policies, helps frame protection around attendees, facilities, and partners, providing a clear safeguard so one unexpected incident doesn’t disrupt programming, delay approvals, or place future events at risk. Campus event insurance is a specialized, short-term liability policy designed to protect event organizers, student groups, and universities from financial losses related to bodily injury, property damage, and legal claims during events held on college or university property.

Liability Insurance for Campus Spaces and Public Access

Liability coverage forms the foundation for events held across campus spaces with public access, and you should review it carefully with your insurance company to ensure it provides complete protection. Event general liability responds to third‑party bodily injury and property damage that can arise in quads, student centers, auditoriums, classrooms, and rented halls, whether caused by trip hazards, crowd movement, or accidental damage to university property. Clear communication with an insurance contact helps organizers confirm that coverage aligns with the scope of the event and campus expectations. Taking a business‑focused approach to coverage design helps event hosts satisfy venue contract requirements while ensuring protection is thorough and complete, reducing the risk that gaps in liability coverage could jeopardize approvals or future campus events.

Limits should be calibrated to venue size, expected attendance, and the nature of activities such as performances, fairs, demonstrations, or lectures. Campus event insurance policies often provide general liability limits starting at $500,000 and commonly ranging up to $1,000,000 or $2,000,000 per occurrence for bodily injury or property damage to third parties. Universities and event venues often require these limits as a minimum standard. This coverage typically includes legal defense costs, even if a claim ultimately lacks merit, and it helps protect event organizers from expensive lawsuits.

Certificates, Additional Insureds, and Booking Rules

Certificates, additional insured status, and booking rules often serve as the final checkpoints before organizers approve a campus event, and they frequently create tight timelines. Most university risk or facilities offices require a certificate of insurance (COI), a formal document that outlines the types of insurance coverage in place, including policy limits, effective dates, and named insured parties. The COI names the institution, and sometimes specific departments or property managers, as an additional insured for campus venues, with precise wording and dates that match the event details. It’s important to submit the COI request early and confirm that coverage terms align with campus requirements.

Universities often require organizers to list the institution, along with its employees and sometimes affiliated departments, as additional insureds to protect them from claims arising from the event organizer’s negligence. With short-term event insurance, organizers should extend coverage periods beyond showtime to include setup, live hours, and teardown, so the protection reflects how campus spaces are actually used. Reviewing the policy premium in advance and verifying it supports the full event timeline helps prevent delays in keys, access badges, room access, and final approvals that can otherwise stall a well‑planned event.

Student Orgs, Departments, and Outside Groups

Students collaborating in a university setting, representing planning and coordination for campus events and insurance considerations.

Student organizations, academic departments, and outside groups often operate under different insurance expectations when hosting events on campus, making it important to obtain clarity early in the planning process. Student organization event insurance may apply to routine club activities, while a department frequently serves as the official sponsor and institutional representative, for larger or higher‑risk events under broader campus event insurance guidelines designed to address potential accidents and claims. This structure supports risk transfer, shifting the financial burden of accidents or lawsuits away from the university and onto the insurance provider, helping protect institutional budgets from unexpected claims.

Outside organizations, vendors, or community partners are typically required to provide their own evidence of insurance before accessing campus facilities, often as part of a formal agreement with the university. Clearly identifying who is responsible for coverage, what documentation must be obtained, and when separate policies or certificates are required helps avoid last‑minute confusion, supports compliance with venue contract requirements, and ensures events move forward smoothly toward timely approval. Campus event insurance also protects student organization officers and members from being personally liable for injuries or damages connected to the event.

Orientation, Club Fairs, and High-Footfall Activities

Orientation programs, club fairs, and other high‑footfall activities create some of the busiest and most risk‑prone moments on campus, where event liability exposure increases as attendance grows. Without event insurance, even minor injuries or property damage incidents during high-traffic events can result in costly claims that may create significant financial hardship for organizers or sponsoring groups. Welcome week events and tabling sessions concentrate crowd movement, temporary structures, and electrical cords, raising the chance that accidents may occur, from trip hazards to minor injuries. Because of this elevated risk, proactive planning is an important investment in keeping events safe and approved.

Organizers should structure orientation week insurance, club event insurance, and event general liability so that they properly cover eligible activities and align liability limits with queueing layouts, temporary signage, and dense foot traffic across outdoor plazas and indoor concourses. Addressing these exposures in advance helps reduce incidents, supports smooth operations, and ensures campus events can proceed confidently during the most active times of the year.

A group of college students meeting on campus, representing student-organized events that may require campus event insurance.group of students meeting a new friend with a handshake. lifestyle concept.

Commencements, Ceremonies, and Large Special Events

Commencements, graduations, and hooding ceremonies introduce a unique concentration of risk due to temporary staging, expanded seating, audiovisual equipment, and large, emotionally charged crowds, often spread across multiple days and involving students, families, and institutional clients. Commencement ceremony insurance, paired with equipment and staging coverage, should account for rehearsals, formal processions, and peak‑attendance moments, not just the main ceremony itself. Organizers should also note how coverage applies if schedules shift or they must cancel events, and ensure they clearly understand the terms before final approvals and payment deadlines.

Overflow viewing areas on lawns, courtyards, or in arenas add additional exposure, as do rented risers, tents, and broadcast setups that may trigger damage to premises rented to you. Matching insurance limits and effective dates to the full scope of activities helps protect institutions from claims, manage financial commitments, and ensure these milestone events run smoothly from first rehearsal to final celebration.

A graduation ceremony with students in caps and gowns, representing large campus events that require event insurance coverage.

Vendors, Caterers, and Third‑Party Partners: Event Insurance Coverage Considerations

Vendors, caterers, and other third‑party partners introduce additional risk layers that must be clearly managed for campus events, especially when their employees are working on site or interacting with attendees. Catering teams, production companies, rental firms, and entertainers are typically required to furnish vendor and caterer COIs as proof of insurance, along with any necessary endorsements naming the institution as additional insured for campus venues. These requirements are often spelled out as a specific subject of the event policy review and must be satisfied before load‑in or service begins. Many campuses and venues require proof of liability insurance before allowing vendors or event organizers to operate on-site, making insurance a prerequisite for event approval rather than an optional safeguard.

Collecting, reviewing, and tracking this proof ensures that you keep contractual obligations with the appropriate parties, not the university or event sponsor, and that you fully meet venue contract requirements and campus risk management standards. Proper oversight helps prevent coverage gaps, supports smoother approvals, and keeps events running without last‑minute compliance or documentation issues.

Short-Term Policies and Special Endorsements

Short‑term policies and special endorsements help campus event insurance stay precise, flexible, and mindful of cost. Short‑term event insurance, such as one‑day or weekend policies, can be tailored across a range of event types to mirror exact event windows, ensuring essential activities like setup, live hours, and teardown are fully covered without extending protection beyond what’s needed. Many universities use tenant user liability insurance policies (TULIP), which provide low-cost, short-term liability coverage specifically designed for third-party users hosting events on campus. This targeted approach helps protect organizers from unnecessary exposure while keeping overall insurance costs manageable.

Where applicable, organizers should also consider adding a special event alcohol endorsement that aligns with campus policy, approved security plans, and local regulations. Structuring coverage this way allows insurance to match the real risk profile of the event, supporting smoother approvals, clearer compliance, and effective protection without paying for coverage that falls outside the event’s true scope.

Alcohol and Liquor Liability Considerations

If organizers serve alcohol at a campus event, standard liability coverage may not be sufficient. Organizers often need liquor liability coverage to protect against alcohol-related incidents, such as injuries or property damage caused by intoxicated attendees. Liquor liability coverage specifically addresses claims arising from the serving, sale, or distribution of alcohol, including third-party bodily injury and property damage linked to impaired behavior.

Insurers do not always include this coverage automatically, so you often must add it separately depending on the insurer and jurisdiction. In some cases, insurers may restrict availability or require additional underwriting, especially for large events or those open to the public.

Some venues and universities may not approve of events serving alcohol without proof of liquor liability coverage. These requirements may include minimum limits and may mandate trained servers, security presence, or compliance with local alcohol regulations.

A person reviewing an insurance policy document, representing campus event insurance planning and coverage review.

Additional Coverage: Weather, Postponement, and Continuity Plans

In the end, organizers achieve successful campus events by planning not only for what they expect but also for what might change without warning, and by ensuring they can quickly obtain coverage that responds when disruptions arise. Outdoor festivals, concerts, commencements, and ceremonies are especially vulnerable to weather shifts, utility interruptions, and other issues that can impact schedules and attendance. Using an online process to purchase liability insurance makes it easier to secure the right protection early and keep planning on track.

You can often purchase event insurance online in minutes, receive instant quotes based on event size, location, and activities, and in many cases obtain your policy immediately after completing payment. Pairing event cancellation and postponement options with comprehensive university event insurance and clearly defined contingency plans, such as backup venues, adjusted timelines, or alternate power, helps safeguard prepaid expenses and contractual commitments. This proactive approach to risk management allows organizers to respond confidently, limit financial exposure, and preserve a positive experience for attendees, partners, and the campus community alike.

Sources:

https://www.nfumutual.co.uk/news-and-stories/insurance-to-run-an-event/
https://cfo.asu.edu/short-term-insurance
https://bene-marc.com/insurance-for-college-and-university-special-events
https://risk.ucmerced.edu/events-activities/outside-groups-event-insurance
https://studentcenter.uci.edu/events/insurance-coverage-information-for-events/
https://www.utoledo.edu/depts/risk/eventliabilityinsurancestudentorganizations.html

From student‑run LAN nights on campus to pro‑am tournaments staged in full‑scale arenas, eSports event organizers, and esports teams themselves, begin assuming risk the moment players, spectators, and high‑value technology come together. Universities, gaming lounges, convention planners, sponsors, and tournament operators all face potential exposure, including equipment damage, participant injuries, cyber disruptions, venue liabilities, and event interruptions that can quickly lead to significant financial losses.

Special event insurance for eSports, often referred to as esports event or gaming tournament insurance, is designed to address these unique risks. Coverage can help protect attendees and competitors, safeguard expensive hardware and production setups, satisfy venue and sponsor insurance requirements, and provide financial protection when cancellations, postponements, or unexpected incidents threaten revenue, prize pools, or contracts.

In a fast‑moving, tech‑driven environment where schedules, broadcasts, and sponsorships are tightly connected, the right insurance coverage helps ensure that a single incident doesn’t derail competition timelines, impact eSports teams, or undermine budgets, allowing organizers to focus on gameplay and production, not unintended financial losses. In many cases, these risks must be addressed not only for financial protection, but also to meet venue requirements and provide proof of insurance before an event can proceed.

Event Liability Insurance for Spectators, Venues, and Public Access

General liability insurance forms the foundation of protection for esports events by addressing third‑party bodily injury and property damage for which organizers may be held responsible, often referred to as public liability coverage for eSports events. Common exposures include trip hazards created by power and network cabling, congested player pits and exhibition areas, and accidental damage caused by screens, displays, truss systems, or stage elements. These incidents fall squarely within spectator and visitor liability risks.

As eSports events scale, the potential severity and frequency of these claims may increase alongside audience size, venue footprint, and production complexity. Coverage limits should be carefully calibrated to expected attendance and physical setup, including LED walls, lighting rigs, player booths, demo stations, and other temporary installations. Policies should also include protection for damage to premises rented to you, a key consideration when working with arenas, convention centers, and campus facilities.

With properly structured general liability insurance in place, event organizers can confidently manage public access, meet venue and contractual requirements, and reduce the financial impact of unexpected accidents, helping ensure that isolated incidents don’t evolve into costly claims, disputes, or event‑threatening losses.

Additional Insurance Coverages eSports Events May Require

Beyond general liability insurance, eSports event organizers often need additional coverage to address the full scope of operational and financial risks involved in running a tournament.

These may include:

  • Excess Liability Insurance: Provides additional protection above primary general liability limits, which may be required for large venues such as convention centers or arenas.
  • Professional Liability (Errors & Omissions): Covers claims related to tournament mismanagement, technical failures, or breach of contract that could lead to financial loss.
  • Directors and Officers (D&O) Insurance: Protects esports organizations and leadership from claims related to corporate decision-making and governance.
  • Event Cancellation Insurance: Reimburses non-refundable expenses and lost revenue if an event is canceled, postponed, or interrupted due to unforeseen circumstances.
  • Prize Indemnity Insurance: Allows organizers to offer large prizes (such as skill-based or promotional rewards) without bearing the full financial risk upfront.
  • Employment Practices Liability (EPLI): Covers claims related to staffing issues such as wrongful termination, discrimination, or contract disputes.
  • Workers’ Compensation Insurance: Required in many jurisdictions if staff are employed during the event, covering workplace injuries and lost wages.

These coverages can help esports organizers manage both operational risks and financial exposure while meeting venue, sponsor, and regulatory requirements.

Protecting Special Events: Participants, Teams, and Accident Medical Coverage

While esports doesn’t involve full‑contact play, participant injuries still happen, from slips and falls backstage to repetitive strain, equipment‑related incidents, and crowd‑related issues during load‑in or live competition. Risks can increase during high‑stakes competition, in temporary venues, or when extreme weather introduces heat, power, or access challenges. Left unaddressed, these situations can lead to delays, reputational impact, financial losses, or lawsuits related to medical care and duty of care obligations.

A large arena filled with spectators watching a live esports tournament, representing esports event insurance for high-attendance gaming events.

Participant accident medical coverage, often included in special event insurance or broader eSports event insurance programs, helps cover medical expenses regardless of fault. This allows organizers to respond quickly, reduce disputes, and keep matches and broadcasts on track. For tournaments with tight schedules and contractual commitments, this coverage plays an important role in protecting players while minimizing operational and legal disruption. This type of coverage is especially important for events involving large numbers of participants, minors, or extended play sessions, where the likelihood of injury or health-related issues increases.

Equipment and Tech Powering the eSports Industry: PCs, Consoles, and Broadcast Rigs

eSports events depend on high‑value, highly sensitive technology, making equipment one of the most significant risk areas for organizers, teams, and production partners. Tournament PCs, consoles, servers, cameras, switchers, and audio systems play a critical role in professional player performance and face heightened risk during load‑in, setup, live production, and strike, when teams frequently move, mount, and connect equipment under tight timelines. Power outages, surges, or sudden shutdowns can further compound exposure, potentially damaging hardware or interrupting matches and broadcasts.

A well‑structured equipment policy covers owned PCs and consoles, along with hired and non‑owned equipment supplied by studios, broadcasters, sponsors, or venues. Aligning equipment values to full replacement cost, and including goods‑in‑transit coverage with door‑to‑door protection, helps ensure the policy covers losses arising from theft, accidental damage, transport incidents, or electrical events. With the right coverage in place, organizers and teams can reduce financial strain, protect competitive integrity, and focus on delivering uninterrupted gameplay and production rather than managing costly technical setbacks.

In addition to physical hardware, esports companies should also consider the value of digital assets, including game licenses, proprietary software, and stored data. These assets, along with gaming equipment, are vulnerable to theft, vandalism, and accidental damage, particularly in high-traffic environments.

Cyber Threats to Networks: Managing Cyber Risks and DDoS Resilience

eSports events rely on stable, secure networks, and even brief disruptions can have outsized consequences for safety, competitive integrity, and event continuity. A congested or targeted network can pause gameplay, disrupt live streams, impact employees working production or operations, and frustrate clients, sponsors, and spectators. In more severe scenarios, prolonged outages can force teams to delay matches or even cancel entire events, triggering refund obligations and damaging reputation. Registration systems, Wi‑Fi portals, and streaming platforms also introduce exposure to data breach and privacy risks affecting attendees, partners, and internal teams.

A person working on a laptop in a dimly lit environment, representing event planning and risk management for esports event insurance.

Coverage such as cyber event interruption (DDoS) protection, combined with data breach, privacy liability, and extra expense coverage, helps organizers manage lost revenue, recovery costs, and third‑party claims. In an environment where uptime is critical and expectations are high, proactive cyber resilience plays a key role in protecting people, platforms, and relationships, helping ensure esports tournaments remain online, compliant, and on schedule.

As the eSports industry continues to grow, organizers are also facing increased regulatory and compliance expectations around data protection and digital operations. Insurance plays a critical role in supporting compliance efforts while helping mitigate emerging risks such as cyberattacks, data breaches, and platform outages that could otherwise disrupt tournaments or expose organizations to legal action.

eSports Insurance Essentials: Venue Contracts, COIs, and Additional Insureds

Venues may require policy dates that explicitly span load‑in, setup, live event hours, and teardown to avoid coverage gaps, especially for third‑party injury or property damage claims involving the venue. Organizers should also be aware that short‑term policies are often subject to a minimum premium, regardless of event duration, which can affect budgeting and coverage decisions.

Equally important is ensuring that endorsement language closely matches venue contract terms. Misalignment can delay access credentials, restrict rigging or electrical work, or create conflicts with curfews and load‑out schedules. By confirming coverage, endorsements, limits, and premium requirements well in advance, organizers can reduce last‑minute friction, meet contractual obligations, and keep production timelines, and venue relationships, running smoothly.

How eSport Companies Work with Vendors, Sponsors, and Talent Partners

eSport events may depend on a broad network of third‑party partners, production companies, merchandise sellers, food and beverage vendors, sponsors, talent teams, and other eSport businesses, each introducing their own operational risks and liability exposure. These partners can create additional risk through staffing, equipment, temporary structures, branded activations, and use of logos or content tied to intellectual property rights. To reduce coverage gaps, organizers should collect and review vendor and sponsor COIs in advance and clearly define insurance responsibilities, indemnification, and IP usage terms within contracts.

Professional video production cameras filming a live esports or gaming event, representing esports event insurance for streamed and broadcast competitions.

Insurance Coverage for Event Cancellation, Postponement, and Extra Expense

Esports events operate on tight schedules and complex dependencies, making even well‑planned special events vulnerable to disruptions beyond an organizer’s control. Power failures, venue outages, severe weather, network interruptions, or vendor service breakdowns can force last‑minute changes that lead to postponements, relocations, or full cancellations. Event cancellation insurance, when included as part of comprehensive gaming tournament coverage, helps protect prepaid expenses such as venue deposits, talent fees, travel, production costs, and contracted services when a covered interruption occurs.

When paired with extra expense coverage, this protection also supports rapid response efforts, such as securing alternate venues, extending service hours, restoring critical infrastructure, or rerouting broadcasts, to keep competitions running when possible. In an environment where a single delay can cascade across match brackets, streams, and sponsor obligations, event cancellation insurance provides financial stability and operational flexibility, allowing organizers to adapt quickly and maintain confidence among partners, participants, and audiences.

Right-Sizing Limits for Multi-Day LANs

A group of esports players celebrating a win during a competitive gaming event, representing esports event insurance for organized tournaments.

As multi‑day events expand across extended schedules, multiple halls, and high‑stakes finals, thoughtful insurance planning becomes just as critical for eSport companies as brackets and broadcasts. Structure insurance coverage to reflect peak‑attendance days, total on‑site equipment values, comprehensive PC and console coverage, and the full scope of production, streaming, and live services, not just opening‑day assumptions. This ensures protection keeps pace with how the event operates.

Equally important, policy dates must span the entire event lifecycle, covering rehearsals, qualifier rounds, load‑in, live competition, and teardown. By aligning insurance cover with real‑world operations and securing a personalized quote tailored to event size, duration, and risk profile, organizers can close gaps early and ensure coverage holds steady from the first keystroke to the final load‑out.

Sources:

https://www.miller-insurance.com/sectors/sports-and-entertainment/esports-insurance/
https://gosuperscript.com/broker/gaming-esports/
https://esportsinsurance.com/quote/gaming/
https://www.clydeco.com/en/insights/2024/11/the-rise-of-cybersecurity-threats-in-esports
https://www.o2sportsinsurance.com/how-traditional-sports-insurance-can-apply-to-esports/
https://smartfinancial.com/esports-insurance

From weekly services to seasonal picnics, community fundraisers, and mission trips, religious organizations take on real responsibility the moment an event is announced. With attendees, volunteers, and often borrowed or public venues involved, even a minor incident can create unexpected liability.

Special event insurance designed for faith‑based needs, including religious event insurance, church event insurance, and ministry event liability coverage, helps protect missions, budgets, and communities. With the right coverage in place, congregations and ministries can focus on gathering, serving, and celebrating with confidence.

Core Liability Coverage for Services, Picnics, Church Events and Fundraisers

General liability coverage is the foundation of protection for services, picnics, and fundraisers, responding to third‑party bodily injury or property damage that can occur during gatherings on church property or at rented parks and halls. These potential risks, commonly addressed through public liability for church events and fundraising event insurance, increase as attendance grows and activities expand, from slip‑and‑fall incidents to damage to premises rented to you.

Thoughtfully selected coverage helps absorb associated legal fees and claims costs, with limits aligned to crowd size and event type, whether it’s outdoor worship, a community picnic, or a fundraiser featuring bake sales and silent auctions, so one unexpected incident doesn’t disrupt ministry operations or financial stability.

Venues, Municipal Permits, and COIs

Insurance paperwork approval process for religious event coverage and permits

Securing the right venue often goes hand in hand with meeting municipal requirements, and that typically means providing a certificate of insurance for events (COI). Rented facilities and city parks frequently require proof of insurance that can provide coverage meeting venue and municipal standards, including naming the venue or municipality as an additional insured for dates spanning setup through teardown.

Closely aligning endorsement language with permit requirements helps prevent last‑minute delays, supports access approvals, key releases, and any necessary road or space closures, and reduces the risk of uncovered claims or financial loss. With proper documentation in place, events stay on schedule and partnerships with local authorities remain strong.

Volunteers, Ushers, and Partnership Roles

Volunteers play a central role in religious gatherings and other special events, and their involvement directly shapes the overall risk profile. Greeters, ushers, kitchen helpers, and volunteer musicians interact closely with attendees, handle equipment, and manage food service or crowd flow, each activity introducing potential exposure that should be addressed through volunteer liability coverage as part of a broader nonprofit event insurance strategy.

It’s essential to confirm that volunteers are fully covered under the event policy and understand how that protection applies to their specific duties. At the same time, third‑party partners such as caterers, rental companies, entertainers, or security providers should carry their own insurance, with vendor COIs collected in advance as a standard business practice. Clearly defining roles and verifying coverage helps ensure responsibilities are shared appropriately and reduces gaps that could lead to disputes or uncovered losses after an incident.

Food Service, Potlucks, and Bazaars

Shared meals, potlucks, bake sales, and community bazaars are often the heart of religious gatherings, but they also introduce added risk, especially during large gatherings. Food service and potluck liability becomes a concern as shared dishes and concessions increase product liability exposure, while serving lines and crowded tables can create congestion and trip hazards common at festivals and bazaars hosted at most venues.

Food vendor at community event emphasizing vendor insurance needs for religious gatherings

Even informal setups, such as homemade dishes or temporary concession stands, should follow essential food safety practices, ensuring proper labeling, controlling temperatures, and maintaining clean preparation areas. Reviewing festival and bazaar insurance to ensure it contemplates food sampling, on‑site sales, and temporary kitchens helps faith organizations host welcoming, well‑attended events without leaving gaps in protection.

Youth Activities, Camps, Outreach Programs and Off-Site Trips

Youth activities, camps, and off-site trips actively engage children and teens, but they also present unique risks that dedicated youth activity insurance can address. Programs such as children’s choirs, youth game nights, retreats, day trips, and off‑site events require thoughtful supervision, age‑appropriate staffing, and clear planning for transportation, facility layout, and emergency exits. Many common accidents, from minor slips and sports injuries to transportation‑related incidents, can arise even in well‑run programs.

Organizations can quickly address injuries by combining these efforts with participant accident medical coverage. This approach keeps families informed about what is covered and helps manage out-of-pocket expenses. As important, maintaining clear incident documentation demonstrates due care, supports transparency with parents and guardians, and allows faith organizations to manage youth‑focused events responsibly and with confidence.

Tents, Stages, and Borrowed Equipment

Pop‑up tents, portable stages, sound systems, and seating are essential components of many religious gatherings, especially large events, but they also introduce added exposure to weather, impact, and handling damage. Wind gusts can topple tents and temporary structures, cables can strain audio equipment, and frequent setup and teardown increase the likelihood of loss. These realities make tent and temporary structure coverage, along with hired equipment and sound system coverage, critical considerations when planning an event.

Review event policies to ensure that coverage limits and valuations accurately reflect the full replacement cost of rented or borrowed equipment. Clearly define who is responsible for any damage to rented premises, whether the equipment belongs to a vendor, another congregation, or a municipality. To streamline planning and facilitate clearer decision-making, many organizations use online quoting systems or consult their insurance advisors early in the process to confirm coverage. By taking these steps, you can protect budgets, avoid disputes, and ensure that shared or temporary equipment is properly addressed before the event day.

Outdoor religious gathering with tents showing liability and weather coverage considerations

Alcohol Policies for Receptions and Dinners

Most religious gatherings are alcohol‑free, but certain receptions, dinners, or milestone celebrations may include limited wine service, particularly during a multi‑day event or special observance. Host liability insurance should closely match the venue’s requirements and how the organizers serve alcohol. Clear policies around staffing, ID checks, service limits, and designated or fenced service areas help reduce exposure to liability claims while maintaining a respectful, well‑managed environment.

Church leaders can confirm that coverage expectations align with event operations by reviewing these details in advance. This proactive approach enables them to manage receptions responsibly and minimize financial or reputational risks.

Weather, Postponement, and Event Cancellation

Unexpected conditions are a constant reality for outdoor and large‑scale religious events, where rainouts, heat advisories, or utility failures can force last‑minute schedule changes. Because many venues require financial commitments well in advance, these disruptions often carry real costs, including rebooking fees, lost deposits, and attendee refunds. Cancellation coverage protects you against event cancellations, weather issues, and postponements, addressing these situations as outlined in the terms of the insurance policy.

As part of a broader nonprofit event insurance strategy, this coverage helps protect prepaid expenses and vendor obligations when circumstances are beyond an organizer’s control. Planning for weather‑related and operational interruptions in advance allows faith organizations to make safety‑first decisions while minimizing the budget impact of an unavoidable change.

Rainy weather conditions highlight cancellation risks for outdoor religious events

Right-Sizing Limits, Dates, and Documentation

Insurance providers ensure effectiveness by aligning coverage details with the actual operation of an event and meeting the venue’s additional insured requirements.ements. Whether planning worship services, community outreach programs, or larger special events, limits under religious event insurance and broader church insurance should reflect expected attendance, venue expectations, and higher‑exposure elements such as youth programming. A properly issued certificate of insurance for events is most effective when coverage dates clearly span load‑in through strike.

Effective risk management requires consistent incident reporting procedures and clear volunteer briefings before each event. These practices promptly document issues and efficiently process claims, thereby protecting faith organizations throughout the entire process.

Sources:

https://www.ajg.com/industries/religious-insurance-consulting/
https://westernfinancialgroup.ca/How-to-Insure-Your-Faith-Based-Organization
https://agspecialtyinsurance.com/news/insurance-religious-organizations/
https://westernfinancialgroup.ca/What-to-Know-about-Faith-Based-Insurance
https://covenantcares.com/blog/protecting-churches-ministries-faith-based-organizations-with-the-right-insurance/
https://atlasinsuranceagency.com/blog/empowering-faith-a-comprehensive-guide-to-insurance-for-religious-organizations-part-1/
https://1225united.com/insight-resources/insurance-coverage-for-synagogues-mosques-faith-communities